
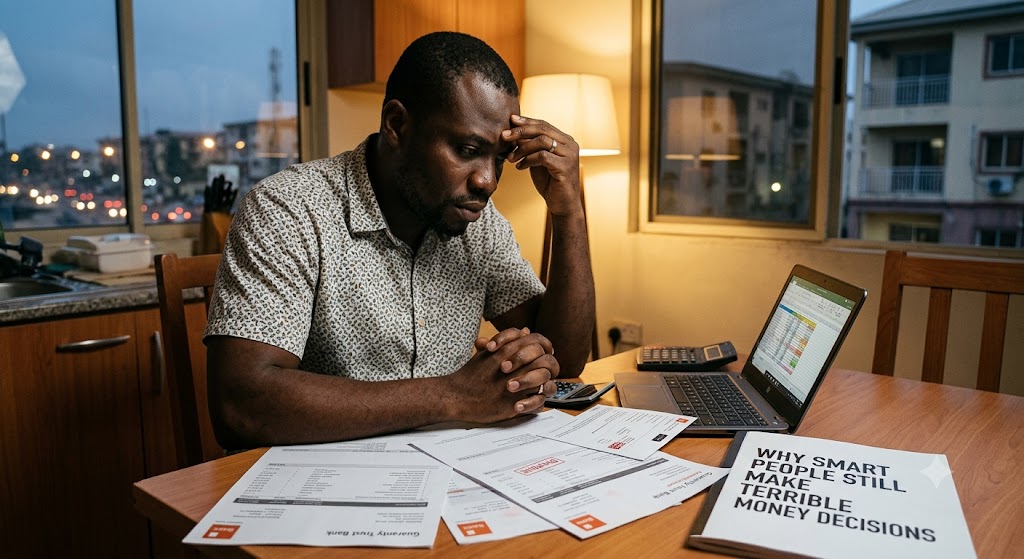
If intelligence alone guaranteed financial success, universities would produce millionaires in large numbers every year, professors would dominate lists of the world’s wealthiest individuals, and every person with multiple degrees would enjoy complete financial freedom. Reality tells a very different story. Around the world, brilliant engineers struggle with debt, highly educated doctors live from one payday to the next, successful lawyers file for bankruptcy, and talented professionals with impressive careers constantly worry about money. At the same time, there are people with average academic backgrounds who quietly build wealth, own valuable assets, invest wisely, and enjoy financial peace. This contrast reveals one important truth that many people overlook. Being smart is not the same as being financially wise.
One of the biggest misconceptions about money is believing that intelligence naturally leads to better financial decisions. Intelligence certainly helps people solve problems, understand complex information, and perform well in school or at work, but money operates differently. Money is deeply connected to emotions, habits, beliefs, discipline, patience, and behaviour. It rewards consistency more than brilliance and punishes emotional decisions regardless of a person’s IQ. Many financially successful individuals are not necessarily the smartest people in the room. They simply understand how to control their emotions, delay gratification, and make sensible financial choices over long periods.
Many intelligent people believe they can outsmart the financial system. Because they excel in their careers, they assume they can predict markets, identify perfect investments, or avoid common financial mistakes. This overconfidence often becomes expensive. Someone who has always been praised for being intelligent may find it difficult to admit they know very little about personal finance. Instead of learning from experts, reading financial books, or seeking professional advice, they trust their instincts. Unfortunately, money has a way of humbling everyone who believes they are smarter than risk itself.
Education also plays a surprising role in this problem. Schools spend years teaching mathematics, science, history, literature, and countless other subjects, yet very few students graduate with practical knowledge about budgeting, investing, taxes, insurance, retirement planning, or wealth creation. A person can calculate advanced equations but struggle to understand compound interest. They may write complex computer programs while carrying credit card debt with extremely high interest rates. Academic excellence and financial literacy are simply not the same thing.
Another reason smart people make poor money decisions is because they confuse a high income with wealth. Earning a large salary creates the illusion of financial security. Many professionals believe that as long as more money continues entering their bank account, they are financially successful. However, wealth is not measured by income alone. Wealth is determined by what remains after spending, what grows through investments, and what continues generating income even when someone stops working. Countless high-income earners have little savings because every increase in earnings is matched by an increase in lifestyle expenses.
Lifestyle inflation quietly destroys many intelligent professionals. A promotion leads to a more expensive house. A salary increase leads to a luxury vehicle. A bonus leads to designer clothing, expensive holidays, premium gadgets, and restaurant bills that become normal instead of occasional treats. Because their income continues growing, they rarely notice how quickly their expenses consume every additional pound, dollar, euro, or naira they earn. Years later they discover they have impressive possessions but very little financial freedom.
Emotions remain one of the strongest influences on financial behaviour. Intelligence does not eliminate fear, greed, envy, pride, or anxiety. During economic booms, smart people often become overly optimistic and invest recklessly because everyone else appears to be making money. During economic downturns, the same intelligent individuals panic and sell investments at significant losses. Markets repeatedly demonstrate that emotional reactions often produce worse financial outcomes than carefully planned decisions.
Social pressure also affects intelligent people more than many realise. Success often comes with expectations. Professionals may feel pressured to maintain appearances that reflect their education or career status. They buy expensive watches, luxury vehicles, prestigious homes, and designer brands because they believe successful people are expected to own these things. Their spending becomes a performance designed to impress colleagues, relatives, neighbours, or social media followers. Unfortunately, appearances cannot build wealth. In many cases, they slowly destroy it.
Modern social media has intensified this problem. Every day people are exposed to carefully selected moments from other people’s lives. Exotic holidays, luxury apartments, expensive meals, new cars, and business achievements appear continuously on mobile screens. Even highly intelligent individuals subconsciously compare themselves with these carefully edited images. Instead of asking whether they can comfortably afford something, they begin asking whether they can afford to appear less successful than others. This dangerous mindset encourages unnecessary spending and weakens long-term financial discipline.
Another common mistake involves confusing expertise in one field with expertise in every field. A brilliant surgeon understands medicine exceptionally well, but that knowledge does not automatically translate into investment expertise. A successful software developer may know how to build sophisticated applications while knowing very little about portfolio diversification. Intelligence sometimes creates a false sense of competence outside one’s actual area of knowledge. This phenomenon causes many smart individuals to underestimate financial complexity.
Many intelligent people also underestimate the importance of simple financial habits because they constantly search for sophisticated solutions. They want advanced investment strategies, complicated tax structures, and high-risk opportunities promising extraordinary returns. Meanwhile, some of the most successful wealth-building principles remain surprisingly ordinary. Spending less than you earn, investing consistently, avoiding unnecessary debt, maintaining an emergency fund, diversifying investments, and allowing compound growth to work over decades often produce better results than constantly chasing the next financial breakthrough.
Patience is another quality frequently overlooked. Intelligent people often expect rapid progress because their educational and professional achievements rewarded quick learning and measurable performance. Financial growth rarely follows that pattern. Building meaningful wealth usually requires years of disciplined investing, careful budgeting, and consistent saving. There are very few genuine shortcuts. Those seeking instant riches often become easy targets for fraudulent investment schemes, unrealistic business opportunities, and promises of guaranteed high returns.
Financial scams frequently target intelligent individuals precisely because scammers understand human psychology. Rather than appealing to ignorance, sophisticated fraudsters appeal to intelligence by presenting complicated investment strategies filled with technical language, exclusive opportunities, confidential information, and promises unavailable to ordinary investors. Many highly educated victims lose significant amounts of money because they believe they have discovered opportunities others cannot understand. In reality, complexity often hides deception rather than genuine value.
Why Smart People Still Make Terrible Money Decisions
Debt is another area where intelligence offers surprisingly little protection. Many intelligent people justify borrowing because they believe future earnings will easily cover repayments. While this may sometimes prove true, unexpected life events such as illness, redundancy, economic recessions, or business failures can quickly transform manageable debt into overwhelming financial stress. Borrowing against future income always carries uncertainty because the future cannot be guaranteed.
Impulse spending is often associated with poor financial education, but intelligent people experience it as well. Instead of making emotional purchases without explanation, they become experts at rationalising them. They convince themselves that expensive purchases are investments, networking opportunities, productivity improvements, or rewards for hard work. Their logical reasoning simply provides better excuses for emotional decisions. The result remains the same. Money leaves faster than it accumulates.
Many financially unsuccessful intelligent people also neglect opportunity cost. Every financial decision involves sacrificing an alternative. Buying an expensive luxury vehicle means giving up potential investment returns. Spending excessively on status symbols reduces future financial flexibility. Choosing immediate consumption often delays long-term wealth creation. Wealthy individuals consistently evaluate not only what they are buying but also what they are giving up in the process.
Another overlooked factor involves childhood beliefs about money. Intelligence develops through education and experience, but financial attitudes often begin forming during childhood. People raised in households where money caused constant conflict may develop fear around investing. Those who grew up believing wealthy individuals were dishonest may subconsciously sabotage their own financial success. Others may associate spending with happiness because purchases temporarily replaced emotional security. These deeply rooted beliefs continue influencing adult financial behaviour regardless of educational achievement.
Perfectionism also creates financial problems. Intelligent people frequently hesitate because they want complete certainty before making decisions. They spend years researching investments instead of investing. They endlessly compare business ideas without launching one. They postpone retirement planning until they understand every detail. Unfortunately, perfection rarely exists in finance. Time often matters more than flawless decision-making. Someone who begins investing modest amounts consistently usually outperforms someone who waits years searching for the perfect opportunity.
Another reason smart people struggle financially is that they overvalue information while undervaluing execution. Reading fifty books about investing accomplishes very little without actually investing. Watching hundreds of financial videos changes nothing if spending habits remain unchanged. Knowledge creates potential, but disciplined action creates results. Financial success depends less on what people know and more on what they consistently practise.
Many intelligent professionals become trapped in the belief that earning more will eventually solve every financial problem. They focus entirely on increasing income while ignoring spending behaviour. Yet countless examples prove that financial problems often expand alongside income. Without financial discipline, every salary increase simply funds larger expenses. Wealth grows when income increases faster than lifestyle, not when lifestyle expands alongside every pay rise.
Risk management represents another important difference between intelligence and wisdom. Intelligent individuals sometimes become fascinated by high-risk investments because they enjoy solving complex problems and pursuing exceptional outcomes. However, successful investors understand that protecting capital matters just as much as growing it. Avoiding catastrophic losses often contributes more to long-term wealth than achieving spectacular short-term gains.
Relationships also influence financial decisions significantly. Smart people sometimes ignore warning signs in business partnerships, marriages, friendships, or family arrangements because they assume logical agreements will prevent future conflict. Money, however, often exposes emotions that logic cannot predict. Lending large sums to relatives, guaranteeing loans for friends, or entering informal business agreements without proper documentation has damaged countless intelligent individuals financially.
Consumer marketing further complicates financial decision-making. Companies invest billions studying psychology to influence purchasing behaviour. Advertisements create urgency, scarcity, fear of missing out, and emotional attachment. Loyalty programmes, limited-time offers, personalised recommendations, and targeted online advertising affect everyone, regardless of intelligence. Recognising these influences helps people make more deliberate financial decisions rather than reacting automatically.
The desire for recognition also encourages poor financial choices. Many people measure success externally rather than internally. They seek admiration through visible consumption instead of invisible wealth. The expensive vehicle parked outside often attracts attention, while the investment portfolio quietly growing in the background remains unnoticed. Truly wealthy individuals frequently understand that financial security is more valuable than public admiration.
Building financial wisdom requires humility. The smartest financial decision someone can make is admitting there is always more to learn. Financial markets evolve, tax regulations change, investment opportunities shift, and economic conditions fluctuate. Remaining curious, seeking reliable information, and accepting occasional mistakes allows continuous improvement. Pride, on the other hand, often prevents people from correcting costly financial habits.
Developing healthier financial behaviour begins with recognising that money is primarily behavioural rather than mathematical. Creating a realistic budget, tracking expenses, automating savings, investing regularly, avoiding unnecessary debt, building emergency reserves, and reviewing financial goals consistently may appear ordinary, but these habits quietly transform financial futures. Extraordinary wealth often results from ordinary actions repeated consistently over many years.
It is equally important to separate self-worth from net worth. Intelligent people sometimes attach their identity to financial success, making every investment loss or business setback feel like personal failure. This emotional connection encourages desperate attempts to recover losses quickly, leading to even riskier decisions. Viewing financial mistakes as learning experiences rather than personal weaknesses encourages better judgement and long-term resilience.
Financial freedom ultimately belongs to those who master themselves before attempting to master money. Intelligence remains valuable, but discipline is often more profitable. Knowledge matters, but consistent behaviour matters even more. The world is filled with brilliant people who understand complicated theories yet struggle with simple financial habits. At the same time, countless ordinary individuals quietly accumulate wealth by making sensible decisions year after year.
The greatest lesson is that money rarely rewards intelligence alone. It rewards patience when others rush, discipline when others overspend, humility when others become overconfident, and consistency when others constantly change direction. Smart people who recognise these truths gain a powerful advantage because they stop relying solely on intelligence and begin building financial wisdom. When knowledge is combined with emotional control, long-term thinking, and disciplined habits, money becomes a tool for creating freedom instead of a constant source of stress. The smartest financial decision anyone can make is accepting that brilliance is only the beginning. Lasting wealth is built not by how clever someone appears, but by the quality of the financial decisions they make every single day.

EarnSmartOnline.com.ng is dedicated to helping readers make smarter financial decisions through practical guides on online income, personal finance, technology, digital business, and wealth creation. Our goal is to provide reliable, easy-to-understand, and actionable content that empowers individuals to earn smarter, build sustainable income streams and achieve long-term financial success.
Recommended: Start Earning Online
- Ultimate Affiliate Marketing Program — learn affiliate marketing with a done-for-you sales system ($15). Check it out
- The Newbie Affiliate Guide — the beginner-friendly starter guide (~$6.68). Check it out
- Easy Dollar Maker — earn in dollars uploading AI images and videos from your phone ($17). Check it out
Disclosure: These are affiliate links. If you buy through them, I may earn a commission at no extra cost to you.



