
What is a mutual fund?
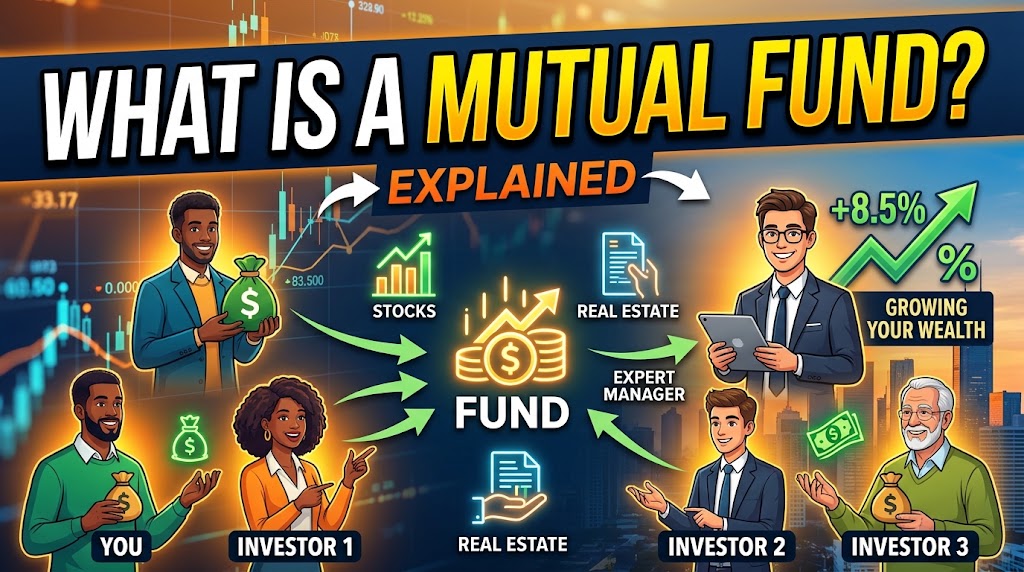
What is a mutual fund? This is one of the most common questions asked by people who are beginning to learn about investing and want to understand how they can put their money to work without having to personally select and manage every investment. A mutual fund is an investment vehicle that collects money from many investors and pools those funds together to invest in a portfolio of assets such as shares, bonds, money market instruments or other securities, depending on the objectives of the fund.
The basic idea is relatively simple. Instead of an individual investor taking all their available money and trying to build a diversified investment portfolio alone, they can invest in a mutual fund and become part of a larger pool of investors. The fund is professionally managed according to a stated investment strategy, and each investor owns units or shares representing their portion of the fund.
Understanding what is a mutual fund is important because mutual funds can provide ordinary investors with access to a diversified collection of investments without requiring them to individually research, purchase and monitor every security in the portfolio. However, mutual funds are not automatically profitable, risk free or suitable for everyone. Like other investments, they involve risks, costs and decisions that investors should understand before putting their money into them.
Imagine that ten thousand people each want to invest but do not have the time, expertise or confidence to research hundreds of different investments. Instead of each person independently building a portfolio, they contribute money to a common fund. The combined money can then be invested according to the fund’s stated strategy. Each investor participates in the performance of the overall portfolio according to the amount they have invested.
This pooling of money is one of the defining characteristics of a mutual fund. The investor does not necessarily choose each individual asset held by the fund. Instead, the investor chooses the fund based on its investment objective, strategy, historical performance, risk level, fees and other characteristics.
For example, an equity mutual fund may invest primarily in shares of companies. A bond fund may focus mainly on bonds and other fixed income securities. A money market fund may invest in short term, relatively liquid instruments. A balanced or mixed fund may combine different asset classes.
This means that when someone asks what is a mutual fund, there is no single answer that describes every mutual fund perfectly. Different funds have different objectives, strategies, risk levels and portfolios.
One of the biggest attractions of mutual funds is diversification. Diversification means spreading investments across different assets rather than putting all your money into one investment. The idea is that if one investment performs poorly, other investments in the portfolio may perform better and help reduce the impact.
Suppose an investor puts all their money into the shares of one company. If that company experiences serious financial difficulties and its share price falls dramatically, the investor could suffer a significant loss. A diversified fund might hold shares in many companies, meaning that the poor performance of one company may have a smaller effect on the entire portfolio.
Diversification does not eliminate investment risk. A mutual fund can still lose money, particularly when the market or asset class in which it invests performs poorly. However, diversification can reduce the risk associated with relying heavily on a single investment.
Another important feature of mutual funds is professional management. A mutual fund is generally managed by investment professionals who make decisions about what securities the fund should buy, hold or sell based on its investment mandate.
This can be attractive to people who do not want to spend their evenings analysing company financial statements, studying market movements or monitoring individual investments. Instead, they can select a fund that matches their objectives and allow the fund manager to manage the portfolio within the rules governing that fund.
However, professional management does not guarantee good performance. Fund managers can make incorrect decisions, markets can fall and economic conditions can change. Investors should therefore never assume that a professionally managed fund cannot lose money.
When learning what is a mutual fund, it is also important to understand how investors make money from them. Depending on the type of fund and its structure, investors may benefit when the value of the underlying investments increases. Some funds may also generate income from dividends, interest or other investments held within the portfolio.
The value of an investor’s holding generally reflects the value of the fund’s underlying assets, after applicable expenses and liabilities are taken into account. If the assets held by the fund increase in value, the value of the investor’s units may increase. If the underlying investments decline in value, the value of the investor’s units can decline as well.
This is why investing in a mutual fund should not be confused with placing money in an ordinary savings account. A savings account may provide interest according to its terms, while a mutual fund’s value can fluctuate depending on the investments it holds.
One term investors often encounter when learning about mutual funds is net asset value, commonly called NAV. The NAV represents the value of the fund’s assets minus its liabilities, calculated according to the fund’s valuation rules. The NAV is used in determining the value of units or shares in the fund.
Understanding NAV can help investors understand what they are buying and how the value of their investment is calculated. However, investors should not assume that a fund with a lower NAV is automatically cheaper or better than one with a higher NAV. The NAV by itself does not determine whether an investment represents good value.
There are several broad categories of mutual funds. Equity funds primarily invest in shares and are generally designed for investors seeking long term growth, although they can experience significant fluctuations. Because shares can rise and fall substantially, equity funds may carry more market risk than some conservative investment funds.
Bond funds invest primarily in bonds and other fixed income securities. Their performance can be influenced by interest rates, credit quality, economic conditions and other factors. Some bond funds may be designed to generate income while providing a different risk profile from equity funds.
Money market funds generally focus on short term money market instruments. They are often used by investors seeking liquidity and relatively lower volatility compared with many equity investments. However, lower volatility does not mean zero risk, and the exact characteristics depend on the fund and the regulations governing it.
Balanced or mixed funds combine different types of assets. A fund might hold a combination of shares, bonds and other investments. The purpose is often to provide a balance between growth, income and risk.
There can also be specialised mutual funds that focus on particular industries, geographical markets, investment strategies or asset classes. This means investors should never select a fund simply because it is called a mutual fund. They need to understand exactly what the specific fund invests in.
One of the biggest mistakes beginners make is assuming that every mutual fund is automatically diversified enough. A fund may hold many investments but still concentrate heavily on one sector, country, asset class or investment theme. Investors should examine the fund’s portfolio and investment strategy rather than relying solely on its name.
Fees are another important consideration. Mutual funds can have various costs associated with managing and operating the fund. Depending on the specific fund, these may include management fees, administrative expenses, distribution costs, transaction expenses or other charges.
Even seemingly small fees can matter over a long investment period because they reduce the amount of money that remains invested. Investors should therefore understand the total cost of owning a fund before committing their money.
This does not mean the cheapest fund is always the best fund. A fund with a particular strategy or level of professional management may have higher costs for legitimate reasons. The important point is that investors should understand what they are paying for and consider whether the potential benefits justify the costs.
Another question that naturally follows what is a mutual fund is whether beginners can invest in one. In many markets, mutual funds are specifically designed to make investing accessible to a broad range of investors. Minimum investment requirements vary significantly between funds, providers and countries.
Some funds may allow relatively small initial investments, while others may require substantially more capital. Investors should check the specific requirements of the fund they are considering rather than assuming every mutual fund has the same minimum investment.
The process of investing may involve selecting a fund, completing the required account opening and identity verification procedures, reviewing the fund documentation and making an investment according to the provider’s procedures.
Investors should also understand how they can withdraw their money. Some mutual funds allow investors to redeem their units, subject to the fund’s rules and applicable processing times. Others may have specific restrictions or conditions.
Liquidity is therefore another factor that should be considered before investing. Money needed for immediate emergencies generally should not be placed into an investment without understanding how quickly it can be accessed and what could happen to its value if the investment needs to be sold at an inconvenient time.
This is particularly important because investment markets do not always rise when investors need money. Someone who invests money that they will need next month could be forced to sell during a market decline and realise a loss.
This brings us to one of the most important principles of personal finance. Investing should normally be connected to a financial goal and a suitable time horizon. Someone saving for a goal that is only a few months away may have very different investment needs from someone investing for retirement several decades into the future.
Risk tolerance also matters. Risk tolerance refers to how much investment uncertainty or potential loss an investor can reasonably tolerate. Two people with identical incomes may have completely different attitudes towards investment risk.
One person may be comfortable watching the value of their portfolio fluctuate because they are focused on a long term goal. Another person may become extremely anxious after seeing a temporary decline and sell their investment at the worst possible time.
Knowing yourself as an investor is therefore just as important as knowing the fund.
Past performance is another area where investors need to be careful. A fund that performed extremely well in previous years may not produce the same results in the future. Market conditions change, investment strategies can encounter difficult periods and past winners can underperform.
Investors should therefore avoid choosing a mutual fund solely because it has recently produced impressive returns. They should consider the fund’s objectives, strategy, risk, fees, portfolio, management, performance over appropriate periods and suitability for their own financial goals.
It is also important to distinguish between a mutual fund and buying individual stocks. When you buy an individual company’s shares, your investment is directly tied to that company. When you invest in a mutual fund, your money is generally spread across a portfolio selected according to the fund’s strategy.
This can make mutual funds attractive to investors who want diversification without having to select every investment themselves.
However, mutual funds also mean that investors surrender some control over individual investment decisions. If a fund manager buys a company that you personally dislike, you generally cannot instruct the manager to remove that specific company from the portfolio unless the fund’s structure provides such a choice.
This is one of the trade offs of professional management.
Another important consideration is taxation. The tax treatment of mutual funds varies between countries and can depend on the type of fund, the income generated, distributions, capital gains and the investor’s individual circumstances. Investors should understand the applicable tax rules in their jurisdiction and seek qualified professional advice when necessary.
For investors in Nigeria and other countries, it is particularly important to verify that the fund provider and investment product are properly authorised and regulated by the relevant financial authorities. Investors should not transfer money simply because someone on social media promises unusually high or guaranteed returns.
Promises of guaranteed extraordinary profits should be treated with extreme caution.
Legitimate investing involves risk. The higher the promised return, particularly when it is presented as guaranteed, the more questions an investor should ask.
Investors should also be cautious about sending money to individuals rather than verified investment providers. They should independently verify the identity of the fund manager, the regulatory status of the fund, the official documentation, the investment strategy, the fees and the process for withdrawing funds.
So, what is a mutual fund in the simplest possible terms? It is a pooled investment vehicle where money from multiple investors is combined and invested in a portfolio of assets according to a defined investment strategy. Investors own a portion of the fund and participate in its financial performance.
The appeal of mutual funds comes from several features working together. They can provide diversification, professional management, accessibility and convenience. But these advantages do not remove risk. A mutual fund can lose value, charge fees and perform differently from what an investor expects.
The best way to approach mutual funds is therefore not to ask whether they are good or bad. A better question is whether a particular mutual fund is appropriate for your financial goals, investment horizon, risk tolerance and overall financial situation.
Someone who understands what is a mutual fund is already one step closer to making more informed investment decisions. But understanding the definition is only the beginning. Before investing, an individual should investigate the specific fund, read its documentation, understand what it owns, learn about its fees, consider its risks and confirm how money can be invested and withdrawn.
Personal finance is not about finding one magical investment that makes everyone wealthy. It is about making decisions that are appropriate for your circumstances and maintaining a disciplined approach over time.
Mutual funds can be one tool within that broader financial strategy. They can help investors gain exposure to a diversified portfolio without having to personally select every asset. For someone who values simplicity and professional management, that can be a significant advantage.
At the same time, investors should never confuse simplicity with safety. The fact that a mutual fund makes investing easier does not mean the investment itself is risk free.
The most important lesson is to understand what you own. Do not invest simply because a friend recommended a fund, because an influencer promoted it, because its recent returns look impressive or because someone promised that you cannot lose money.
Understand the investment before committing your money.
When you know what a mutual fund is, how it works, what it invests in, what it costs and what risks it carries, you can evaluate it more rationally. That knowledge can help you move from simply saving money to thinking more strategically about how your money could potentially grow over the long term.
Ultimately, the question what is a mutual fund is much more than a request for a dictionary definition. It is an entry point into understanding pooled investing, diversification, professional investment management and the relationship between risk and potential return.
For a beginner, that understanding can be extremely valuable. The more you learn about how different investment products work, the less likely you are to make financial decisions based purely on hype, fear or promises.
A mutual fund is not a shortcut to guaranteed wealth. It is a financial tool. Like any tool, its usefulness depends on how well you understand it and whether it is appropriate for the job you need it to perform.
That is the foundation every new investor should build before putting money into the market.

EarnSmartOnline.com.ng is dedicated to helping readers make smarter financial decisions through practical guides on online income, personal finance, technology, digital business, and wealth creation. Our goal is to provide reliable, easy-to-understand, and actionable content that empowers individuals to earn smarter, build sustainable income streams and achieve long-term financial success.
Recommended: Start Earning Online
- Ultimate Affiliate Marketing Program — learn affiliate marketing with a done-for-you sales system ($15). Check it out
- The Newbie Affiliate Guide — the beginner-friendly starter guide (~$6.68). Check it out
- Easy Dollar Maker — earn in dollars uploading AI images and videos from your phone ($17). Check it out
Disclosure: These are affiliate links. If you buy through them, I may earn a commission at no extra cost to you.



