
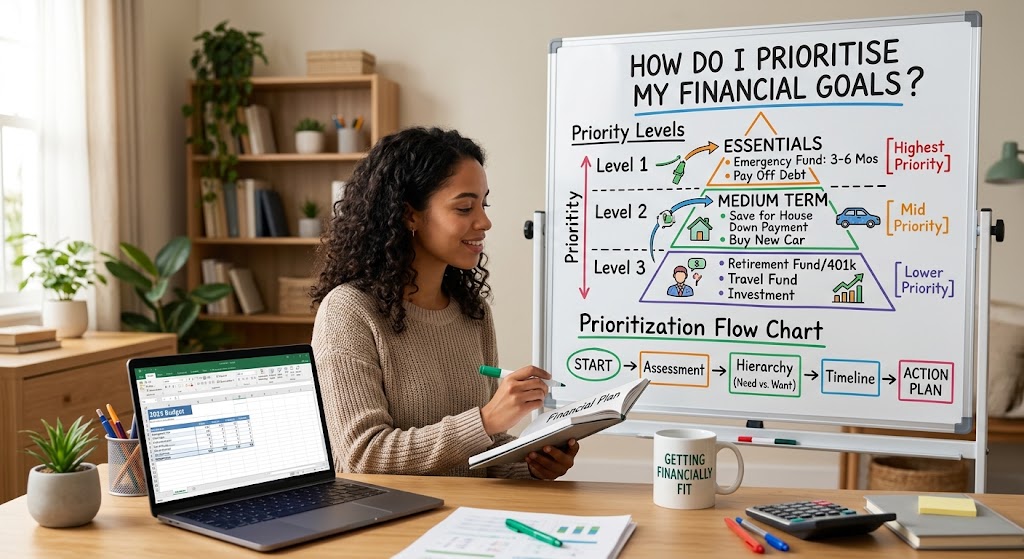
How do I prioritise my financial goals?
How do I prioritise my financial goals? This is one of the most important questions anyone can ask when trying to take control of their money. Having financial goals is a good start, but having too many goals without knowing which ones deserve attention first can make your finances confusing, stressful and difficult to manage. You may want to build an emergency fund, pay off debt, buy a house, start a business, invest for the future, save for your children’s education, prepare for retirement and still have enough money to enjoy your life. The problem is that your income may not be large enough to accomplish everything at the same time.
This is why learning how to prioritise your financial goals matters. Financial success is not necessarily about pursuing every goal simultaneously. It is about understanding which goals are most important, identifying which ones are urgent, allocating your available resources intelligently and knowing when to focus on one objective before moving towards another. When you prioritise properly, even a modest income can be directed towards meaningful financial progress.
The first thing to understand is that not every financial goal has the same level of importance. Some goals protect you from financial emergencies, some reduce financial pressure, some create future opportunities and others simply improve your lifestyle. If you treat every goal as equally important, you may end up spreading your money so thinly that none of your goals receives enough attention.
For example, imagine that you have limited savings and several financial objectives. You want to take a holiday, buy a new phone, pay off expensive debt, build an emergency fund and invest for retirement. All five goals may be legitimate, but they should not necessarily receive the same amount of money at the same time. Paying expensive debt and building basic financial security will usually deserve greater priority than upgrading a phone or taking an expensive holiday.
A useful way to answer the question “How do I prioritise my financial goals?” is to begin with your financial survival and security. Before thinking about wealth creation, make sure the foundation of your finances is reasonably stable. This means knowing how much money you earn, understanding your essential expenses, identifying your debts and determining whether you have any emergency savings.
Your essential expenses are the costs you need to maintain your basic standard of living. These may include housing, food, transportation, utilities, healthcare, insurance, communication and other necessary obligations. Understanding these expenses gives you a realistic picture of how much money is actually available for financial goals.
Once you know your essential expenses, consider building an emergency fund. An emergency fund is one of the most important financial goals because life rarely follows a perfect plan. Your car may require an unexpected repair. Your income could temporarily decrease. A family emergency could require immediate spending. A major household expense could appear without warning.
Without emergency savings, an unexpected expense can force you to borrow money, use expensive credit or abandon other financial goals. Having a financial cushion gives you breathing room and reduces the possibility that one unexpected event will completely disrupt your finances.
The size of your emergency fund depends on your circumstances, income stability and essential expenses. Someone with a highly stable income may approach emergency savings differently from someone whose income changes significantly from month to month. The important point is to establish a financial safety net appropriate for your situation rather than assuming that one fixed number works for everyone.
After establishing basic financial security, look carefully at your debt. High cost debt can become one of the biggest obstacles to achieving long term financial goals because interest continually works against you. If a significant portion of your income is going towards interest and repayments, you have less money available for saving, investing and other objectives.
This does not necessarily mean that every debt must be eliminated before you save or invest anything. Your circumstances matter. But high interest debt deserves serious attention because reducing it can improve your future cash flow and reduce the amount of money you lose to interest.
When prioritising debt, consider the interest rate, balance, repayment requirements and consequences of failing to pay. A debt with a very high interest rate may deserve greater attention than a lower cost debt. You should also make sure that essential payments are kept up to date before directing additional money towards other goals.
Another important consideration is whether a goal is urgent or merely desirable. Urgency is one of the simplest ways to distinguish between competing financial objectives.
Suppose you need to replace a broken vehicle because you rely on it to earn an income. That may be more urgent than saving for a holiday. Suppose your rent is due soon and you have insufficient money to cover it. Paying the rent is obviously more urgent than investing extra money.
This does not mean lifestyle goals are unimportant. It simply means that financial priorities should reflect consequences and timing.
A helpful question to ask is, “What happens if I do not achieve this goal soon?”
If the answer is that you could experience serious financial consequences, the goal probably deserves a higher priority. If the answer is simply that you would have to wait longer for something enjoyable, the goal may be able to move further down your list.
Time is another powerful factor when deciding how to prioritise financial goals. Some goals have deadlines while others become more difficult to achieve if you delay them.
Retirement planning is a good example. The earlier you begin investing for long term goals, the more opportunity your money has to potentially grow through compounding. Delaying a long term financial goal can therefore have a greater impact than simply delaying a short term purchase.
At the same time, you should not use long term investing as an excuse to ignore immediate financial problems. The key is balance. Your financial plan should protect your present while preparing for your future.
You should also separate your financial goals into short term, medium term and long term objectives. Short term goals might include building emergency savings, paying a particular bill or saving for an upcoming expense. Medium term goals might include purchasing a vehicle, funding education or starting a business. Long term goals might include buying property, achieving financial independence or preparing for retirement.
This classification makes your financial goals easier to understand because you can see which objectives require immediate attention and which can be funded gradually over several years.
Another useful approach is to rank your goals according to importance. Instead of simply writing down twenty goals, create three categories such as essential, important and optional.
Essential goals are those that protect your financial stability or prevent serious consequences. Important goals improve your financial position or help you achieve meaningful life objectives. Optional goals are desirable but can be delayed without causing significant financial harm.
This simple classification can dramatically improve decision making.
For example, paying essential household expenses may be an essential goal. Building an emergency fund may also be essential. Paying down expensive debt may be highly important. Investing for retirement may be important and potentially urgent over the long term. Buying the latest smartphone may be optional.
The exact ranking will differ from person to person, but the principle remains the same. Your money should flow towards the goals that matter most.
Income should also influence how you prioritise your financial goals. Someone earning a high income may be able to fund several goals simultaneously. Someone with a limited income may need to focus almost entirely on one or two objectives at a time.
There is nothing wrong with this.
Trying to imitate the financial strategy of someone with a completely different income can create unnecessary frustration. Personal finance is personal because your financial priorities should reflect your income, responsibilities, circumstances and aspirations.
If your income is limited, focus on making meaningful progress rather than trying to accomplish everything immediately. Even a small monthly contribution towards an important goal can establish momentum.
You should also consider your financial dependants. If other people rely on your income, your priorities may be different from those of someone who is financially responsible only for themselves. Parents, caregivers and people supporting family members may need to place greater emphasis on emergency savings, insurance, education and income protection.
This is particularly important because financial decisions do not always affect only the person making the decision.
Another important question is whether your goals support one another. Some financial goals can be combined because progress in one area makes another goal easier.
For example, paying down expensive debt can eventually free up money that can be redirected towards investments. Building an emergency fund can prevent unexpected expenses from forcing you into new debt. Increasing your income can make it easier to save for multiple objectives.
Look for these connections when creating your financial plan.
You should also assign a specific amount and deadline to each major goal. “I want to save more money” is not a particularly useful financial goal because it does not tell you how much you need or when you want to achieve it.
A stronger goal might be to save a specific amount by a specific date. This gives you something measurable to work towards and makes it easier to calculate how much you need to set aside regularly.
Breaking large financial goals into smaller milestones can also make them psychologically easier. A goal that appears enormous can feel impossible, while smaller milestones create visible progress.
For example, someone trying to build a substantial emergency fund can focus first on reaching the equivalent of one week of essential expenses, then one month, then gradually increase the target.
Progress creates motivation.
However, you should be careful not to let motivation replace mathematics. A financial goal must be realistic relative to your income and expenses. If your plan requires saving an amount that leaves you unable to pay essential bills, the plan is not sustainable.
Your financial priorities should therefore be ambitious enough to create progress but realistic enough to maintain.
Another common mistake is constantly changing priorities. Someone may decide to save for a house one month, start a business the next month, focus on investing shortly afterwards and then abandon everything to purchase a car.
Changing goals is sometimes necessary because life changes. But constantly jumping from one objective to another can prevent meaningful progress.
Before changing a financial goal, ask yourself why you are changing it. Is your financial situation different? Has an emergency occurred? Has the goal become less important? Or are you simply distracted by something new?
Financial discipline often means continuing with a sensible plan even when a new opportunity appears.
It is also important to leave room for enjoyment. Prioritising your financial goals does not mean eliminating every form of entertainment or refusing to spend money on things you enjoy.
A financial plan that makes life miserable is unlikely to be sustainable.
You should create room for reasonable discretionary spending while still protecting your important financial objectives. The goal is not to become obsessed with saving every penny. The goal is to make deliberate choices about where your money goes.
Reviewing your priorities regularly is equally important. Your financial goals should not be permanently fixed because your life will change.
You may receive a salary increase, change jobs, get married, have children, start a business, move to a new city, experience an unexpected financial setback or discover that an old goal no longer matters to you.
A financial review every few months can help you determine whether your priorities still make sense.
During the review, look at your income, expenses, debt, savings, investments and progress towards your major goals. Then ask whether your money is still being allocated according to your current priorities.
One of the most powerful questions you can ask yourself is, “If I could achieve only one financial goal this year, which one would have the greatest positive impact on my life?”
The answer can reveal what truly matters.
If paying off a particular debt would dramatically improve your monthly cash flow, that might be your priority. If having emergency savings would reduce constant financial anxiety, that might come first. If your financial foundation is already strong, investing for long term wealth may deserve more attention.
There is no universal answer to the question “How do I prioritise my financial goals?” because financial priorities are deeply connected to individual circumstances. What matters is having a logical framework for making the decision.
Start with survival. Protect your basic needs. Build financial resilience. Address expensive debt. Consider your short term obligations. Prepare for important long term objectives. Then allocate money towards lifestyle goals and other aspirations.
Most importantly, understand that prioritising does not mean abandoning your other goals. It means deciding which goals deserve your strongest financial attention right now.
You can still dream about owning a home while building an emergency fund. You can still want to start a business while paying down debt. You can still plan for retirement while saving for your children’s education. The difference is that you do not allow every goal to compete for the same money at the same time.
Money has limits. Your ambitions may not.
That is why prioritisation is so important.
When you know what matters most, every naira, pound or dollar you save has a purpose. Instead of wondering where your money disappeared at the end of the month, you begin to understand what your money is actually accomplishing.
The ultimate purpose of financial planning is not simply to accumulate money. It is to create greater control over your future.
Learning how to prioritise your financial goals gives you that control. It helps you distinguish between urgent needs and attractive wants, between short term desires and long term objectives, and between spending that moves you forward and spending that simply keeps you busy.
You do not need to achieve every financial goal this month. You do not even need to achieve every goal this year.
You need to know which one matters most now.
Once that becomes clear, the next step is to give it consistent attention.
Financial progress is rarely created by one spectacular decision. It is usually created by repeatedly making sensible decisions about limited resources over a long period.
Your financial goals are competing for your money, but they do not have to compete forever. Prioritise them intelligently, fund them consistently and adjust your plan as your circumstances change.
That is how financial goals become financial results.

EarnSmartOnline.com.ng is dedicated to helping readers make smarter financial decisions through practical guides on online income, personal finance, technology, digital business, and wealth creation. Our goal is to provide reliable, easy-to-understand, and actionable content that empowers individuals to earn smarter, build sustainable income streams and achieve long-term financial success.
Recommended: Start Earning Online
- Ultimate Affiliate Marketing Program — learn affiliate marketing with a done-for-you sales system ($15). Check it out
- The Newbie Affiliate Guide — the beginner-friendly starter guide (~$6.68). Check it out
- Easy Dollar Maker — earn in dollars uploading AI images and videos from your phone ($17). Check it out
Disclosure: These are affiliate links. If you buy through them, I may earn a commission at no extra cost to you.



