
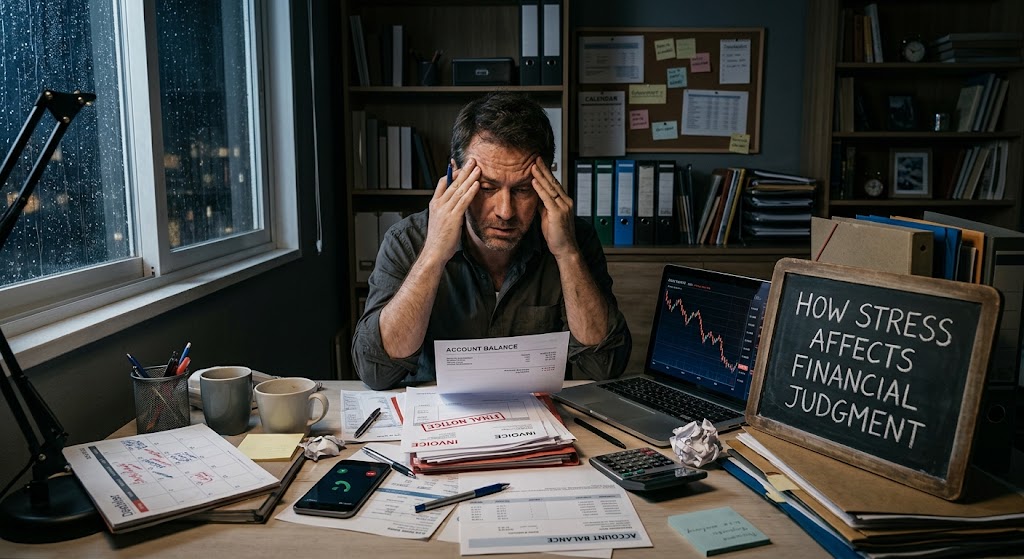
Money decisions are rarely made in a vacuum. Every financial choice is influenced by emotions, circumstances, expectations, experiences and the environment surrounding the person making the decision. When life is calm, it is usually easier to think about money logically. You can compare prices, examine your options, consider long term consequences and decide whether a purchase or financial commitment genuinely makes sense. But when stress enters the picture, financial judgment can change dramatically. This is why understanding how stress affects financial judgment is essential for anyone who wants to build financial stability and make wiser decisions with money.
Stress is a natural response to pressure, uncertainty or perceived danger. It can come from many areas of life, including work, relationships, family responsibilities, unexpected expenses, debt, unemployment, business problems and rising living costs. Financial stress is particularly powerful because money is connected to so many basic needs. Food, housing, transportation, education, healthcare, communication and security often depend on financial resources. When a person feels that there is not enough money to meet these needs, the resulting pressure can affect the way that person thinks, behaves and makes decisions.
Understanding how stress affects financial judgment begins with recognising that stress can narrow your attention. Instead of thinking about the bigger picture, your mind may become focused on the immediate problem in front of you. If you are worried about paying rent, for example, you may concentrate almost entirely on finding money quickly. You may have less mental energy available to consider whether the solution you choose will create a bigger problem next month. The urgent problem becomes more important than the future consequence.
This can explain why someone who normally manages money responsibly may suddenly make a financial decision that appears completely irrational. Stress does not necessarily mean that a person has become careless or financially ignorant. Sometimes the person is simply operating under intense emotional pressure. When the brain is overwhelmed by immediate concerns, long term planning can become much more difficult.
One of the clearest ways stress influences financial behaviour is through impulsive spending. Some people respond to stress by spending money because shopping temporarily creates a sense of comfort, excitement or control. After a difficult day at work, a person may buy clothes, order expensive food, purchase gadgets or spend money on entertainment without carefully considering whether the purchase fits the budget. The spending may provide temporary emotional relief, but the financial consequences can remain long after the emotional comfort disappears.
This creates a dangerous cycle. Stress can lead to spending, spending can reduce available money, reduced money can create more financial pressure, and increased financial pressure can produce even more stress. Before long, the person may find themselves trapped in a pattern where money is being used as an emotional coping mechanism rather than as a tool for achieving meaningful financial goals.
Stress can also cause people to avoid financial information. Someone who is worried about debt may stop checking their bank account. A person struggling with bills may ignore messages from creditors. Someone who is overspending may avoid looking at their transaction history because they are afraid of what they will discover. This avoidance may feel emotionally easier in the short term, but it often makes the financial problem worse.
Ignoring financial reality does not make the problem disappear. In many cases, it allows the problem to grow quietly. An unpaid bill can become additional charges. A missed payment can affect future borrowing opportunities. A small debt can become a much larger obligation when interest and penalties accumulate. Stress therefore has the potential to create a situation where the fear of facing a financial problem becomes more damaging than the original problem itself.
Another important part of understanding how stress affects financial judgment is recognising its influence on risk taking. Under financial pressure, some people become excessively cautious while others become dangerously willing to take risks. A person who desperately needs money may become attracted to promises of quick wealth. They may invest in something they do not understand, participate in questionable schemes, borrow money to invest, gamble or make decisions based on unrealistic expectations.
The promise of solving a financial problem quickly can become extremely attractive when someone feels trapped. A person who has been struggling for months may be more vulnerable to statements such as “double your money quickly” or “make thousands in a few days.” Under normal circumstances, the same person might question the offer. Under intense stress, desperation can overpower caution.
This is one reason financial education should include emotional awareness. Knowing how investments work is valuable, but understanding how your emotions influence your investment decisions is equally important. A financially knowledgeable person can still make poor choices when fear, desperation, excitement or pressure takes control.
Stress can also influence borrowing decisions. When someone needs money urgently, the most important question may become, “How quickly can I get the money?” rather than, “What will this borrowing cost me over time?” That shift in attention can lead people to accept expensive loans, borrow from multiple sources or repeatedly use credit to cover everyday expenses.
Borrowing is not automatically a bad financial decision. Credit can sometimes be useful when used responsibly and for a clearly defined purpose. The problem occurs when stress prevents someone from considering the complete cost of borrowing. A person may focus on the amount they receive today while overlooking the total amount they will eventually repay.
For example, someone facing an urgent financial emergency may be relieved to obtain money immediately. That relief can make the loan feel like a solution. But if repayment creates another financial crisis several weeks later, the original stress has simply been transferred into the future. This is why major borrowing decisions should ideally be made after taking a moment to calculate the complete financial impact.
Stress can also affect our perception of value. When people are emotionally overwhelmed, they may become more focused on immediate affordability than actual value. Something that costs a small amount today may appear harmless, even if repeated purchases of the same kind consume a significant portion of monthly income.
This is particularly relevant to subscription services, convenience spending, frequent food deliveries, unnecessary upgrades and small daily purchases. Individually, each expense may seem insignificant. Collectively, they can become a major financial burden. Stress can make it harder to step back and recognise the pattern.
Another way stress affects financial judgment is through decision fatigue. Every day requires numerous decisions. What to eat, where to go, what to buy, what bills to pay, what work to complete and what responsibilities to handle all require mental energy. When someone is already under significant stress, financial decisions can feel exhausting.
How Stress Affects Financial Judgment
As a result, people may choose the easiest option rather than the best option. They may renew a service automatically rather than compare alternatives. They may buy whatever is immediately available rather than search for a better price. They may delay important financial tasks because they simply do not have the mental energy to deal with them.
This does not mean that every poor financial decision is caused by stress. Personal habits, financial knowledge, social pressure, income levels and individual circumstances all matter. However, stress can magnify existing weaknesses. Someone who already struggles with budgeting may become even less organised under pressure. Someone who tends to shop emotionally may spend more when stressed. Someone who avoids difficult conversations may become even more likely to ignore financial problems.
Social pressure can make this situation even more complicated. When people feel stressed about money, they may compare themselves with others who appear to be doing better. Social media can intensify this comparison. People constantly see images of expensive holidays, new cars, restaurants, fashion, gadgets and seemingly successful lifestyles. What they see is often only a carefully selected version of another person’s life, but stress can make the comparison feel painfully real.
This can encourage spending for appearance rather than necessity. Someone may buy something they cannot comfortably afford because they do not want to feel left behind. They may take on debt to maintain a lifestyle that their income cannot support. They may feel embarrassed about living within their means because they believe everyone else is progressing faster.
The problem is that financial appearances can be deceptive. A person driving an expensive car may be heavily indebted. Someone travelling frequently may be spending savings rather than earning more. A person displaying luxury possessions online may be experiencing serious financial difficulties privately. Stress becomes particularly dangerous when people use other people’s visible lifestyles as a measurement of their own financial success.
Understanding how stress affects financial judgment also requires examining fear. Fear can cause people to make decisions that protect them emotionally in the short term but harm them financially in the long term. For instance, someone who has experienced a financial loss may become so afraid of losing money again that they avoid every form of investment. Keeping all money in cash may feel safer, but inflation can gradually reduce its purchasing power.
At the other extreme, fear of missing out can push stressed individuals into speculative decisions. They may see someone else making money and feel an urgent need to participate. Instead of carefully researching an opportunity, they act because they are afraid that waiting will cause them to miss their chance.
Good financial judgment requires the ability to tolerate uncertainty. Unfortunately, stress can make uncertainty feel unbearable. When people are stressed, they often want immediate answers and immediate solutions. But many worthwhile financial decisions require patience. Saving, investing, building a business, paying down debt and developing financial security usually take time.
One practical way to protect yourself is to create financial rules before stress arrives. Instead of deciding what to do with money during an emotional crisis, establish basic principles while your mind is calm. You might decide that major purchases require a waiting period. You might decide that investments must be researched before money is committed. You might decide that borrowing requires a written repayment plan. You might also establish a minimum emergency fund target.
These rules can act as financial guardrails. They reduce the number of decisions you have to make when emotions are intense. If you have already decided that you will not make major purchases while emotionally overwhelmed, you do not need to debate the issue every time stress appears.
A simple budget can also reduce the influence of stress on financial judgment. Budgeting is not simply about restricting spending. A good budget provides clarity. It tells you what money is available, what obligations must be handled and what amount can reasonably be used for personal spending. When you know your financial boundaries, you are less likely to make decisions based entirely on emotion.
An emergency fund can also reduce financial stress. Unexpected expenses are part of life. Vehicles break down, appliances fail, businesses experience difficult periods and family emergencies can happen without warning. Without savings, every unexpected expense can feel like a disaster. With an emergency reserve, the same expense may still be inconvenient, but it does not necessarily threaten your entire financial structure.
Another useful strategy is to avoid making major financial decisions when emotions are extremely high. If you are angry, frightened, exhausted or overwhelmed, give yourself time whenever circumstances allow. A short delay can create enough mental distance to evaluate the decision more objectively.
This is especially important when dealing with major purchases, investments, loans, business opportunities or financial commitments that cannot easily be reversed. Ask yourself whether you would make the same decision if you were calm. Ask what the decision will cost you in three months, one year and five years. Ask whether you are solving a real problem or simply trying to escape an uncomfortable emotion.
It can also help to discuss major financial decisions with someone trustworthy. A calm second opinion can reveal weaknesses that are difficult to see when you are emotionally involved. The goal is not to allow someone else to control your money. The goal is to create a pause between emotion and action.
Stress management therefore has a direct relationship with financial management. Sleep, physical activity, healthy relationships, rest and reasonable workloads may appear unrelated to money, but they can influence the quality of financial decisions. A person who is constantly exhausted and overwhelmed may have less capacity to think strategically about finances.
Taking care of your mental and emotional wellbeing is not a luxury when it comes to financial stability. It can be part of responsible financial management. The clearer your mind, the easier it becomes to distinguish between what you need, what you want and what you are emotionally trying to escape.
It is also important to understand that financial stress should not always be treated as a personal failure. Sometimes people are under pressure because their income is genuinely insufficient for their essential expenses. Rising costs, unemployment, family responsibilities, business challenges and unexpected emergencies can place enormous pressure on individuals and households. Telling someone to “just budget better” does not solve every financial problem.
However, even when circumstances cannot be changed immediately, understanding how stress affects financial judgment can help a person avoid making a difficult situation worse. The goal is not perfection. The goal is to create enough space between financial pressure and financial action to make better decisions.
The most powerful financial skill may therefore not be knowing how to earn more money, although increasing income can certainly help. It may be knowing how to think clearly when money becomes emotionally difficult. Wealth building requires decisions made repeatedly over time. If stress constantly pushes those decisions in the wrong direction, even a good income can fail to produce financial security.
Your financial future is influenced not only by how much money you earn but also by what you do with money when you are afraid, tired, angry, excited or desperate. This is why emotional discipline deserves a place alongside budgeting, saving, investing and financial education.
When stress appears, pause before reacting. Look at the numbers. Separate the immediate emotion from the long term consequence. Consider alternatives. Ask whether the decision is genuinely necessary. If possible, sleep on major decisions. Give yourself permission to say no to opportunities that require you to act immediately. A legitimate financial opportunity should generally survive reasonable questions and careful consideration.
Ultimately, understanding how stress affects financial judgment can change the way you approach money. Instead of judging yourself harshly for every financial mistake, you can begin examining the conditions that produced the decision. You can identify situations where you are most vulnerable to impulsive spending, unnecessary borrowing, emotional investing or financial avoidance. Once you recognise those patterns, you can build systems that protect you from them.
Money is mathematical, but financial behaviour is deeply emotional. Two people with the same income can make completely different decisions because they respond differently to stress, fear, pressure and uncertainty. The person who learns to manage those emotional influences gains an advantage that cannot be measured simply by looking at a bank balance.
Financial stability is not only about having enough money. It is also about developing the ability to make sensible decisions when life becomes difficult. Stress will inevitably appear. Bills will arrive. Unexpected expenses will happen. Plans will fail. Income may fluctuate. Opportunities will sometimes disappear. The objective is not to create a life without financial pressure. The objective is to become better prepared to respond to pressure without allowing it to control every financial decision.
If you can learn to recognise when stress is influencing your thinking, slow down before making major financial choices, maintain basic financial systems and build enough financial reserves to handle unexpected situations, you give yourself a better chance of protecting your future.
The next time you feel intense pressure about money, remember that the most urgent decision is not always the most important decision. Sometimes the best financial move is to stop, breathe, examine the numbers and give your future self a voice in today’s decision. That small pause can prevent an emotional reaction from becoming a long term financial problem.
Knowing how stress affects financial judgment is ultimately about more than money. It is about understanding yourself. When you understand how fear, pressure, exhaustion and desperation influence your choices, you become better equipped to take control of your financial life. You may not be able to eliminate every source of stress, but you can learn not to let temporary emotions make permanent financial decisions for you.

EarnSmartOnline.com.ng is dedicated to helping readers make smarter financial decisions through practical guides on online income, personal finance, technology, digital business, and wealth creation. Our goal is to provide reliable, easy-to-understand, and actionable content that empowers individuals to earn smarter, build sustainable income streams and achieve long-term financial success.
Recommended: Start Earning Online
- Ultimate Affiliate Marketing Program — learn affiliate marketing with a done-for-you sales system ($15). Check it out
- The Newbie Affiliate Guide — the beginner-friendly starter guide (~$6.68). Check it out
- Easy Dollar Maker — earn in dollars uploading AI images and videos from your phone ($17). Check it out
Disclosure: These are affiliate links. If you buy through them, I may earn a commission at no extra cost to you.



