
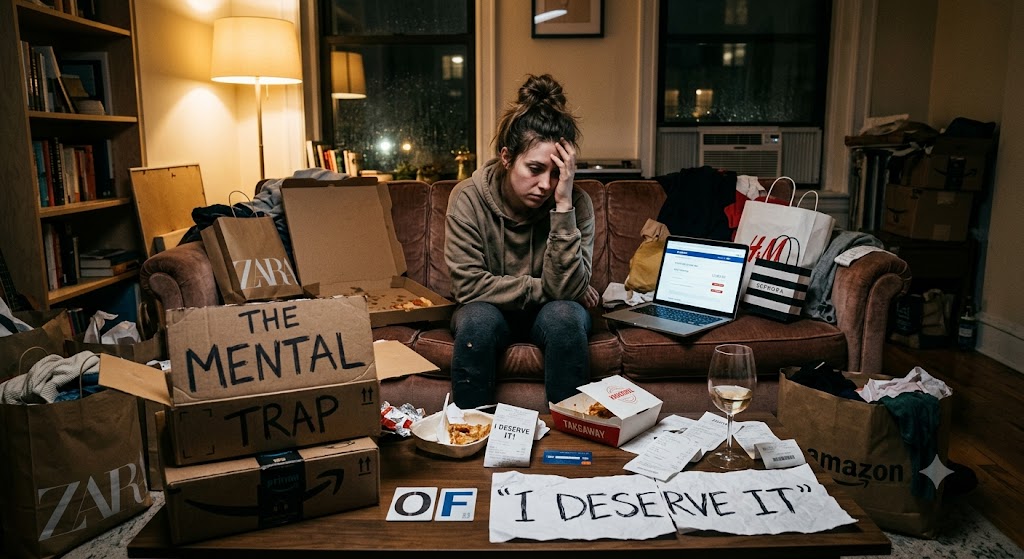
There is a sentence that sounds harmless, comforting and even empowering, yet it quietly influences thousands of financial decisions every day: “I deserve it.” After a stressful week, you deserve the expensive meal. After receiving your salary, you deserve the new phone. After working hard for several months, you deserve the holiday. After dealing with difficult people, you deserve to spend money on something that makes you happy. After sacrificing for everyone else, you deserve to finally think about yourself. None of these statements is automatically wrong. In fact, there is nothing inherently unhealthy about rewarding yourself or enjoying the money you have worked hard to earn. The problem begins when “I deserve it” stops being an occasional reward and becomes a permanent justification for spending, borrowing, upgrading and consuming. The mental trap of “I deserve it”.
This is where the psychology of money becomes fascinating. Financial self sabotage does not always look like irresponsibility. Sometimes it looks like self care. Sometimes it looks like celebration. Sometimes it looks like compensation for everything life has put you through. A person may know exactly what they should be doing with their money, yet still spend it because their emotions convince them that they have earned the right to do so. The purchase may last for minutes, hours or days, while the financial consequences may remain for months or even years.
The mental trap of “I deserve it” becomes particularly powerful because it rarely feels like a bad decision at the moment. When you tell yourself that you deserve something, you are not simply making a financial calculation. You are giving yourself emotional permission. You are telling your brain that this particular decision is justified because of something you have experienced, accomplished or endured. The purchase therefore becomes more than a purchase. It becomes a reward, a symbol of success, a form of relief, an expression of independence or even a way of proving to yourself that your struggles were worth something.
Imagine someone who has spent weeks working long hours. They are exhausted, frustrated and mentally drained. Payday arrives. Instead of looking at their financial goals, they immediately think, “I deserve to enjoy myself.” They spend a significant portion of their income on restaurants, clothes, entertainment and other things they had previously promised themselves they would avoid. For a moment, they feel fantastic. They feel free. They feel rewarded. Then the bills arrive. Savings are lower than expected. Another financial emergency appears. The person becomes stressed again and promises to be more disciplined next month.
Then the next month arrives.
The same cycle begins again.
This is one of the most overlooked financial habits because the individual may genuinely believe they are simply enjoying life. But there is a difference between enjoying your money intentionally and using spending to regulate your emotions. When spending becomes your primary reward system, every difficult experience can become a financial excuse. You work hard, so you spend. You are stressed, so you spend. You are sad, so you spend. You receive good news, so you spend. You experience disappointment, so you spend. You feel bored, so you spend. Eventually, almost every emotional state can become a reason to open your wallet.
The dangerous part is that the human brain is exceptionally good at creating justifications after an emotional decision has already been made. You may see something expensive and want it immediately. Instead of asking whether you can afford it, your mind begins searching for reasons why buying it makes sense. “I have been working hard.” “I never buy anything for myself.” “Life is too short.” “I deserve something nice.” “Everybody else has one.” “I will save next month.” These thoughts reduce the discomfort associated with spending money. They make the decision feel reasonable even when the numbers do not support it.
This is closely connected to instant gratification. Humans naturally tend to value immediate rewards more strongly than future benefits. Saving money often requires you to sacrifice something enjoyable today for something valuable tomorrow. Spending gives you the reward immediately. Saving gives you a promise. Unfortunately, the brain often prefers the reward it can experience right now.
This explains why someone can become excited about buying a new phone while knowing perfectly well that they need to build an emergency fund. The phone is tangible. The emergency fund is abstract. The phone can be held, displayed and enjoyed. Savings sit quietly in an account. One produces an immediate emotional reaction. The other produces security that may not become visible until something goes wrong.
The “I deserve it” mentality exploits this preference for immediate gratification. It turns tomorrow’s security into an unfair sacrifice and today’s pleasure into something that feels morally justified. You are no longer simply deciding between spending and saving. You are emotionally comparing deprivation with reward.
And nobody likes feeling deprived.
This is why financial discipline can be difficult even for people who understand money. Financial knowledge does not automatically produce financial behaviour. You can understand compound interest, budgeting, investing and saving while still making emotionally driven decisions. The problem is not always a lack of information. Sometimes it is the inability to separate what you want from what you have convinced yourself you deserve right now.
The Mental Trap of “I Deserve It”
There is also another psychological layer. Many people grow up believing that hard work should immediately produce visible rewards. You work hard, therefore you should have nice things. You sacrifice, therefore you should upgrade your lifestyle. You earn more, therefore you should spend more. This creates a dangerous relationship between income and lifestyle.
When income increases, expectations often increase with it. A person who previously lived comfortably on a modest salary may receive a significant raise and immediately upgrade their phone, wardrobe, apartment, car, restaurants and holidays. Because the additional spending is connected to additional income, it does not initially feel irresponsible. Yet the person may discover that despite earning more money, they are not significantly wealthier.
This is lifestyle inflation, and “I deserve it” can become one of its strongest psychological engines.
The person is not necessarily trying to become extravagant. They may simply feel that their new income has earned them a better life. There is nothing wrong with improving your quality of life. The danger lies in allowing every increase in income to become an increase in consumption. If every financial improvement immediately disappears into a more expensive lifestyle, your income can grow without your financial security growing alongside it.
Another reason the “I deserve it” trap is powerful is that people often use spending to compensate for areas of life where they feel powerless. Money provides immediate control. If work is frustrating, you can buy something. If a relationship disappoints you, you can go shopping. If you feel unsuccessful, you can purchase something that makes you feel accomplished. If you feel exhausted, you can pay for convenience.
The transaction becomes emotional therapy.
But emotional spending has a problem that therapy, genuine rest and meaningful relationships do not have. The emotional benefit often disappears quickly while the financial obligation remains. A new item may make you feel good for a few hours. A restaurant experience may make you happy for an evening. An impulsive online purchase may provide excitement when the package arrives. But if the money was needed for rent, debt repayment, savings or an important future goal, the emotional reward eventually gets replaced by financial pressure.
This does not mean you should never reward yourself. That would be another unhealthy extreme. Money is not meant to be worshipped, locked away and never enjoyed. The goal of financial maturity is not to eliminate pleasure. It is to make pleasure intentional rather than impulsive.
There is an enormous difference between saying, “I deserve this, so I am buying it,” and saying, “I planned for this reward, I can comfortably afford it, and buying it will not sabotage my priorities.”
The first is emotional permission.
The second is financial choice.
That distinction can completely change your relationship with money.
One useful question to ask before making a purchase is not simply, “Do I deserve this?” You probably do deserve good things. The more important question is, “Can I afford this without damaging something more important?” That question introduces a financial reality check into an emotional decision.
You can deserve the holiday and still need to save first. You can deserve the expensive phone and still decide that your current phone works perfectly well. You can deserve a nice meal and still choose a cheaper option. You can deserve new clothes and still wait for a planned shopping period. Deserving something does not automatically make purchasing it financially wise.
This is an important distinction because deserving and affordability are completely different concepts.
You may deserve a luxury car. That does not mean your current financial situation can support one.
You may deserve a beautiful house. That does not mean taking a huge loan is the right decision.
You may deserve to travel around the world. That does not mean financing the trip with debt is wise.
You may deserve to enjoy your money. That does not mean you should spend money that belongs to your future self.
Your future self is also someone who deserves consideration.
In fact, one of the most powerful ways to overcome this trap is to start thinking of saving as a form of rewarding yourself. Most people view saving as denying themselves something today. What if you viewed it as giving something to yourself tomorrow? Every amount you save is money being transferred from your present desires to your future security.
The person you become five years from now may be grateful that today’s version of you resisted an unnecessary purchase.
The emergency fund you build today may protect you from borrowing tomorrow.
The investment you make today may become part of your financial independence later.
The debt you refuse to create today may give you freedom in the future.
This is delayed gratification, and it is one of the foundations of long term financial success.
The challenge is that delayed gratification does not provide the same emotional excitement as immediate consumption. Saving money rarely gives you the dopamine rush that comes from buying something new. That means you need to deliberately create emotional satisfaction around financial progress.
Celebrate hitting a savings target. Celebrate paying off a debt. Celebrate reaching an investment milestone. Celebrate increasing your income without increasing your lifestyle. Celebrate having money available when an unexpected expense appears. These achievements may not look impressive on social media, but they can radically change your life. The Mental Trap of “I Deserve It”
Another powerful strategy is to create a guilt free spending allowance. Instead of trying to eliminate all discretionary spending, deliberately allocate a percentage or fixed amount of your income towards enjoyment. Once your essential expenses, savings and important financial goals are covered, you can spend that designated amount without feeling guilty.
This changes the psychological equation.
Instead of saying, “I deserve it, so I will spend whatever I want,” you can say, “I planned for enjoyment, and this money is specifically available for it.”
That is freedom with boundaries.
The difference may appear small, but psychologically it is enormous. You are no longer negotiating with yourself every time you want something. You already made the decision when you created the budget. The Mental Trap of “I Deserve It”
It is also useful to recognise the situations that trigger your “I deserve it” thinking. Maybe it happens after a difficult day at work. Maybe it happens immediately after receiving your salary. Maybe it happens when you see your friends posting expensive experiences online. Maybe it happens when you feel rejected, lonely or unsuccessful. Maybe it happens when someone makes you feel that you are not doing enough with your life.
Once you identify your triggers, you can create alternative rewards.
If you are exhausted, rest instead of shopping.
If you are stressed, take a walk, exercise, talk to someone you trust or disconnect from your phone.
If you are celebrating, create a celebration that fits your budget.
If you feel unsuccessful, look at your progress rather than buying something to prove your success.
If social media makes you feel behind, remember that consumption is often displayed far more aggressively than financial sacrifice.
One of the most dangerous things about modern consumer culture is that it constantly creates new reasons for you to feel that your current life is inadequate. There is always a better phone, better car, better wardrobe, better holiday, better house and better lifestyle waiting for you. Marketing rarely says, “You already have enough.” It often says, directly or indirectly, “You could be happier if you bought this.”
When your emotional state becomes connected to consumption, you become extremely easy to persuade.
That is why financial intelligence is not merely about knowing how to calculate interest or create a budget. It is also about understanding your own psychological vulnerabilities.
You need to know when you are most likely to spend irrationally.
You need to understand what emotions influence your financial decisions.
You need to recognise the stories you tell yourself before making purchases.
You need to distinguish between genuine needs, meaningful wants and emotional impulses.
Most importantly, you need to stop treating every desire as an entitlement.
Wanting something does not mean you deserve it immediately.
Working hard does not mean every reward must be financial.
Being tired does not mean spending is the solution.
Feeling successful does not require an expensive display.
And having money does not mean you must spend it.
There is another uncomfortable question worth asking: “What am I trying to prove with this purchase?”
Sometimes the answer reveals more than the price tag.
Perhaps you are trying to prove that you have finally made it. Perhaps you want your friends to respect you. Perhaps you want your family to see that you are successful. Perhaps you want to feel attractive, important or powerful. Perhaps you are trying to make yourself feel better after a painful experience.
If the purchase is carrying an emotional responsibility that has nothing to do with the product itself, pause before buying.
You may discover that you are not actually buying an object. You are buying a feeling.
And feelings purchased with money can become very expensive.
The healthiest relationship with money does not involve constantly denying yourself. It involves making your money serve your values. If experiences matter to you, budget for experiences. If family matters to you, plan for family expenses. If freedom matters to you, prioritise savings and investments. If security matters to you, build an emergency fund. If generosity matters to you, create room for giving.
When your spending reflects your values, you no longer need to justify every purchase with “I deserve it.”
You already know why you are spending.
The ultimate goal is not to stop rewarding yourself. It is to stop using rewards as an excuse to sabotage yourself.
There is nothing wrong with enjoying the fruit of your labour. The problem occurs when you eat today’s fruit and destroy tomorrow’s tree.
Your money should provide enjoyment, but it should also provide options. It should help you handle emergencies, pursue opportunities, reduce financial anxiety and create a future where you are not forced to make every decision based on immediate survival.
The next time you hear yourself say, “I deserve it,” do not automatically reject the thought. Instead, pause and ask yourself a few questions.
What exactly do I deserve?
Can I afford it?
Am I buying this because I genuinely value it or because I need an emotional escape?
Will I still be happy about this purchase next month?
What financial goal could this money support instead?
Am I rewarding myself or borrowing from my future?
Those questions can create enough distance between emotion and action to change the outcome.
Because sometimes you do deserve it.
You deserve peace.
You deserve security.
You deserve freedom.
You deserve opportunities.
You deserve a future where one unexpected expense does not destroy your finances.
And sometimes the thing you deserve most is the discipline to say, “Not today.”
Financial maturity is not about refusing yourself every pleasure. It is about becoming strong enough to choose which pleasures are worth the price. It is understanding that your future is not some stranger waiting somewhere ahead. Your future is you.
So before you spend money simply because you have convinced yourself that you deserve it, remember this: your present self is not the only person who has a claim on your money. Your future self has one too.
And sometimes the most loving financial decision you can make today is not buying yourself something you want.
It is building something your future self will thank you for.

EarnSmartOnline.com.ng is dedicated to helping readers make smarter financial decisions through practical guides on online income, personal finance, technology, digital business, and wealth creation. Our goal is to provide reliable, easy-to-understand, and actionable content that empowers individuals to earn smarter, build sustainable income streams and achieve long-term financial success.
Recommended: Start Earning Online
- Ultimate Affiliate Marketing Program — learn affiliate marketing with a done-for-you sales system ($15). Check it out
- The Newbie Affiliate Guide — the beginner-friendly starter guide (~$6.68). Check it out
- Easy Dollar Maker — earn in dollars uploading AI images and videos from your phone ($17). Check it out
Disclosure: These are affiliate links. If you buy through them, I may earn a commission at no extra cost to you.



