
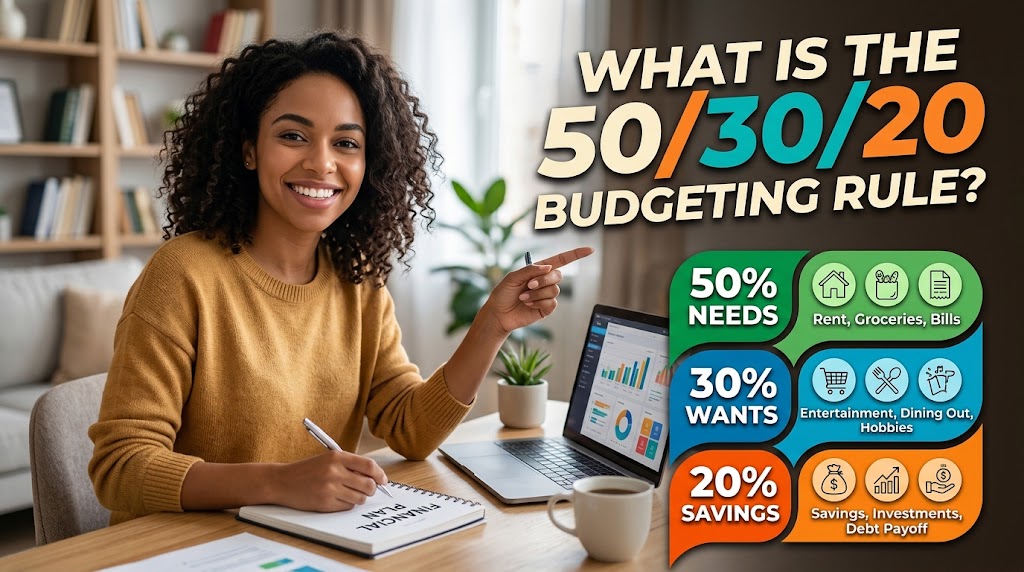
What is the 50/30/20 budgeting rule?
What is the 50/30/20 budgeting rule? This is one of the most common questions people ask when they want to take control of their money without creating an overly complicated financial plan. The 50/30/20 budgeting rule is a simple budgeting framework that divides your after tax income into three broad categories: 50% for needs, 30% for wants and 20% for savings and debt repayment. The idea is to create a straightforward structure that helps you cover essential expenses, enjoy some of your income and still make progress towards your financial goals.
The appeal of the 50/30/20 budgeting rule is its simplicity. Many people struggle with budgeting because traditional budgeting methods can involve tracking dozens of individual expenses, setting separate limits for every category and constantly calculating whether they are staying within their targets. The 50/30/20 rule takes a different approach. Instead of focusing on every small purchase, it gives you three major spending categories that can help you understand where your money is going.
The rule is commonly associated with US politician and former Harvard bankruptcy expert Elizabeth Warren and her daughter Amelia Warren Tyagi, who popularised the framework in their 2005 book All Your Worth. Although the financial circumstances of individuals differ significantly, the underlying principle remains useful: divide your income in a way that balances immediate needs, personal enjoyment and future financial security.
So, what is the 50/30/20 budgeting rule in practical terms? If your monthly take home income is £2,000, for example, the framework would suggest allocating approximately £1,000 to needs, £600 to wants and £400 to savings or debt repayment. If your income is ₦500,000 per month after tax, the same percentages would translate to ₦250,000 for needs, ₦150,000 for wants and ₦100,000 for savings and debt repayment.
The numbers are not meant to be a rigid law. They are a guideline. This distinction is important because everyone’s financial situation is different. A person living in an expensive city may spend more than 50% of their income on basic housing alone. Someone supporting several family members may have essential expenses that make the 50% target unrealistic. A person aggressively paying off high interest debt may decide to put considerably more than 20% towards debt.
The first 50% of the 50/30/20 budgeting rule is designed for needs. Needs are expenses that are essential for maintaining your basic standard of living and meeting important obligations. These can include housing, basic food, utilities, transportation, insurance, healthcare, minimum debt payments and other necessary expenses.
One of the most important parts of using the rule successfully is learning to distinguish between needs and wants. This is not always as simple as it sounds. Food is generally a need, but expensive restaurant meals may be wants. Transportation can be a need, while an unnecessarily expensive vehicle may involve a significant want. Internet access may be essential for someone’s work, while a premium entertainment subscription may be optional.
The second 30% is allocated to wants. Wants are the things that make life more enjoyable but are not essential for survival or basic financial stability. Entertainment, holidays, eating out, hobbies, premium subscriptions, shopping, expensive gadgets and certain lifestyle choices can fall into this category.
This part of the 50/30/20 budgeting rule is important because a good budget should not necessarily make life miserable. Some people approach budgeting as if financial responsibility means eliminating every enjoyable expense. That approach can become difficult to maintain. If your financial plan gives you no room to enjoy your money, you may eventually become frustrated and abandon the plan altogether.
Allowing a reasonable percentage of income for wants can make budgeting more sustainable. It gives you permission to spend some money on enjoyment without feeling guilty, provided your essential expenses and financial goals are being handled responsibly.
The final 20% is intended for savings and debt repayment. This category is particularly important because it focuses on your future rather than only your present circumstances. Depending on your situation, this money could go towards an emergency fund, retirement savings, investments, additional debt payments or other long term financial objectives.
For someone who has expensive high interest debt, putting the entire 20% towards debt repayment may make more sense than investing immediately. Once the debt has been reduced or eliminated, the same money could potentially be redirected towards savings and investments.
Building an emergency fund is another important use of this category. An emergency fund provides a financial cushion when unexpected expenses occur. Car repairs, urgent home expenses, temporary loss of income or unexpected bills can put enormous pressure on someone who has no savings. Having money set aside can prevent a temporary financial problem from turning into expensive debt.
One reason the 50/30/20 budgeting rule has remained popular is that it is easy to calculate. You do not need complicated software or advanced financial knowledge to get started. You simply determine your monthly after tax income and calculate the three percentages.
For example, if your monthly take home pay is ₦300,000, 50% would be ₦150,000, 30% would be ₦90,000 and 20% would be ₦60,000. Those figures give you a starting framework for deciding how much should go towards needs, wants and savings or debt repayment.
If your income is ₦1,000,000 after tax, the theoretical allocation would be ₦500,000 for needs, ₦300,000 for wants and ₦200,000 for savings and debt repayment.
However, the real value of the 50/30/20 budgeting rule is not the mathematics. The percentages are simple. The difficult part is changing behaviour.
Many people know roughly where their money goes but still struggle to control their spending. They may earn enough to cover their bills but have little left at the end of the month. Others may receive a salary increase and immediately increase their lifestyle without increasing their savings.
This is where budgeting becomes a behavioural tool rather than simply a mathematical exercise.
The 50/30/20 budgeting rule can help you identify whether your financial life is balanced. If almost all of your income goes towards needs, your budget may be under serious pressure. If most of your income goes towards wants, you may have an opportunity to reduce discretionary spending. If almost nothing goes towards savings or debt repayment, your future financial security may need more attention.
The rule can therefore serve as a diagnostic tool.
Suppose someone earns ₦500,000 monthly but spends ₦350,000 on housing, food, transportation and other essentials. That already represents 70% of income. Trying to force the person into the traditional 50% needs target may be unrealistic. Instead, the person could recognise that their needs are consuming more than the recommended proportion and look for ways to reduce major expenses or increase income.
This highlights an important lesson: the 50/30/20 budgeting rule should guide your decisions rather than control them.
Housing is often the biggest reason people struggle to fit their finances into the 50/30/20 structure. In many cities, rent can consume a large percentage of take home income. When that happens, cutting small expenses may not solve the problem. Saving a little less on snacks or entertainment will not necessarily compensate for housing that consumes an excessive portion of income.
The same principle applies to transportation and debt. Someone with significant debt obligations may find that their necessary payments consume far more than 50% of their income. In such circumstances, the priority should be improving the overall financial situation rather than pretending that the standard percentages are immediately achievable.
Income level also matters. A person earning a high income may comfortably spend less than 50% on needs while putting more than 20% into investments. Someone on a low income may struggle to cover basic necessities even before considering savings.
This means the 50/30/20 budgeting rule is more useful as a flexible framework than a universal formula.
Another benefit of the rule is that it can make financial conversations easier. Instead of saying, “I spend too much money,” you can look at the three categories and ask specific questions. Are my needs consuming too much of my income? Are my wants taking priority over my financial goals? Am I saving enough for emergencies and the future?
Those questions can reveal patterns that may otherwise remain hidden.
Subscription spending is a good example. A single streaming subscription might not appear significant. Add music, cloud storage, software, fitness services, online memberships and other recurring payments, however, and discretionary spending can become surprisingly large.
The 30% wants category can therefore encourage you to look at all discretionary spending together rather than evaluating each expense in isolation.
The same approach can be applied to eating out, shopping and entertainment. The goal is not necessarily to eliminate these expenses. The goal is to understand their cumulative impact.
One of the biggest mistakes people make with the 50/30/20 budgeting rule is treating the categories as permission to spend a certain amount. If your wants category is 30%, that does not mean you must spend exactly 30%. If you only need 20% for wants, you can redirect the remaining money towards savings, investing or debt repayment.
The percentages are maximum guidelines in some categories, not spending targets that must be reached.
This distinction can significantly accelerate wealth building. Someone who keeps needs below 50% and wants below 30% can potentially direct the difference towards their financial goals.
For example, a person whose needs consume 45% and wants consume 20% has 35% remaining for savings, investing and debt repayment. Over time, that additional saving rate could make a substantial difference.
The rule can also be adapted as your financial circumstances change. When your income increases, you do not necessarily have to increase every category proportionally. One of the smartest ways to use a pay rise is to direct part of the increase towards savings or debt reduction before allowing lifestyle expenses to rise.
This can help protect you from lifestyle inflation, where increased income gradually leads to increased spending without a corresponding improvement in financial security.
For people who are just beginning to budget, the 50/30/20 budgeting rule can be a useful starting point because it does not require perfection. You can begin by reviewing the previous month’s bank statements and categorising your spending.
Add up your essential expenses. Then calculate discretionary spending. Finally, determine how much went towards savings and debt repayment. Compare the results with the 50/30/20 framework.
You may discover that your current spending looks nothing like the suggested percentages. That is not a failure. In fact, discovering the gap is one of the reasons budgeting is valuable.
Once you know where your money is going, you can decide what needs to change.
If your wants are too high, look for expenses that provide little value. If your needs are too high, focus on major expenses rather than obsessing over tiny purchases. If your savings rate is too low, automate your savings immediately after receiving your income rather than waiting to see what remains at the end of the month.
Automation can be particularly effective because it reduces the number of decisions you need to make. When money is automatically transferred into a savings or investment account, you are less likely to accidentally spend it.
The 50/30/20 budgeting rule can also be combined with other financial strategies. You can use it alongside sinking funds, emergency savings, debt repayment plans, retirement planning and investment strategies.
It is not a complete financial plan by itself. It is a framework for organising your cash flow.
Another question people often ask is whether the 50/30/20 rule works for families. It can, although family finances can be more complicated than individual finances. Families may have childcare, school fees, healthcare, housing and other expenses that make the 50% needs category difficult to maintain.
In such situations, the family can use the rule as a reference point while adjusting the percentages according to its actual circumstances.
The same applies to people with irregular income. Freelancers, entrepreneurs and commission based workers may not receive the same amount every month. They may need to calculate their average income over several months or create a budget based on a conservative income estimate.
When income fluctuates, building a larger emergency fund can also become especially important.
Ultimately, what is the 50/30/20 budgeting rule? It is a simple framework designed to help people divide after tax income between essential needs, discretionary wants and financial priorities. The traditional structure suggests 50% for needs, 30% for wants and 20% for savings and debt repayment.
Its greatest strength is simplicity. Its greatest weakness is that real life is rarely simple.
A budgeting system should reflect your actual circumstances. If your needs currently require 65% of your income, pretending otherwise will not improve your finances. If you can save 30% instead of 20%, you do not need to deliberately spend the extra 10%. If you have high interest debt, aggressively reducing it may be more appropriate than following a rigid savings percentage.
The best budget is therefore not necessarily the one that follows the percentages perfectly. It is the one that helps you spend intentionally, avoid unnecessary debt, prepare for emergencies and consistently move towards your financial goals.
The 50/30/20 budgeting rule gives you a simple place to begin. It encourages you to think about what your money is doing today while also considering what you want your money to accomplish tomorrow.
And perhaps that is the most important lesson of all. Personal finance is not simply about earning money. It is about deciding what your money should do once you earn it.
A good budget should help you pay today’s bills without sacrificing tomorrow’s possibilities. It should allow you to enjoy some of your income without allowing temporary pleasures to destroy long term goals. Most importantly, it should give you greater awareness and control over your financial life.
Whether you follow 50/30/20 exactly, adapt it to 60/20/20, 50/20/30 or create an entirely different structure, the underlying principle remains valuable: know what you need, understand what you want and deliberately allocate money towards your future.
That is why the 50/30/20 budgeting rule continues to be one of the easiest budgeting frameworks for beginners to understand and apply. It turns an intimidating subject into three simple questions: How much do I need? How much do I want? And how much am I putting towards my future?
Once you can answer those questions honestly, you are already taking a meaningful step towards better money management.

EarnSmartOnline.com.ng is dedicated to helping readers make smarter financial decisions through practical guides on online income, personal finance, technology, digital business, and wealth creation. Our goal is to provide reliable, easy-to-understand, and actionable content that empowers individuals to earn smarter, build sustainable income streams and achieve long-term financial success.
Recommended: Start Earning Online
- Ultimate Affiliate Marketing Program — learn affiliate marketing with a done-for-you sales system ($15). Check it out
- The Newbie Affiliate Guide — the beginner-friendly starter guide (~$6.68). Check it out
- Easy Dollar Maker — earn in dollars uploading AI images and videos from your phone ($17). Check it out
Disclosure: These are affiliate links. If you buy through them, I may earn a commission at no extra cost to you.



