What is the difference between saving and investing?
When I first started paying closer attention to my finances, I honestly thought saving and investing were almost the same thing. To me, both meant keeping money aside instead of spending everything I earned. If I received money and did not use it immediately, I considered myself financially responsible. It took me some time to realize that although saving and investing are both important parts of building financial security, they serve very different purposes.
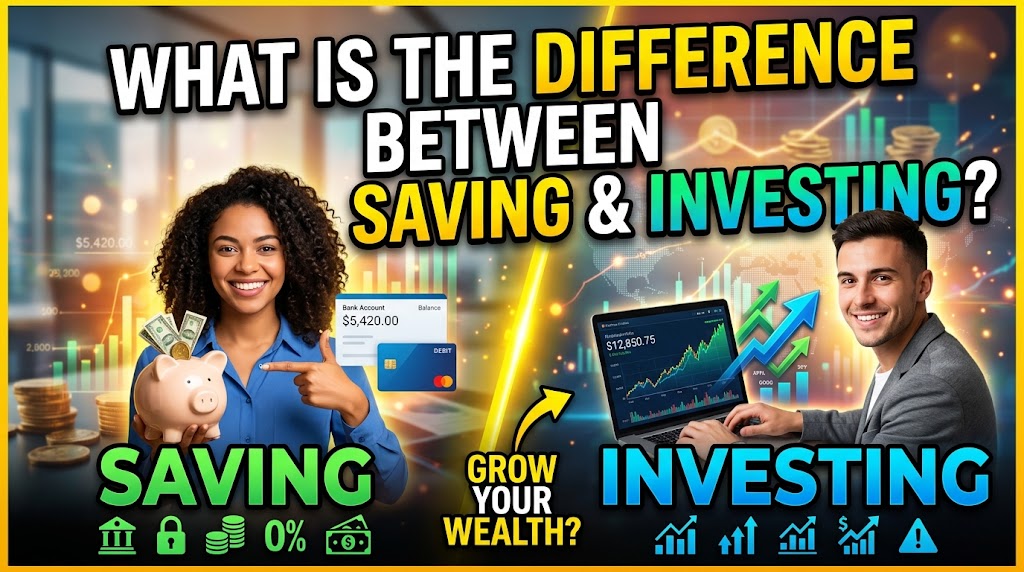
Understanding what is the difference between saving and investing? may sound like a simple financial question, but the answer can completely change the way you manage your money. Saving is generally about protecting money and making it available when you need it, while investing is about putting money into assets or opportunities with the expectation that they may grow or generate returns over time. The difference becomes particularly important when you have specific financial goals and need to decide what your money should be doing.
I remember a period when I was focused mainly on keeping money in my account. Whenever money came in, my first thought was to make sure I did not spend everything. That was not necessarily a bad habit. In fact, developing the discipline to save is one of the most useful financial habits anyone can develop. The problem was that I assumed simply keeping money somewhere was enough to build long term wealth.
Eventually, I started asking myself a more important question. What exactly was the money supposed to accomplish?
That question changed the way I looked at saving and investing.
Saving usually involves setting aside money for future needs while keeping it relatively accessible and exposed to little or no investment risk. A savings account is a common example. You deposit money, keep it there, and can generally access it when you need it. Depending on the account and financial institution, you may receive some interest, but the primary purpose is usually safety and accessibility rather than significant long term growth.
Investing works differently. When you invest, you commit money to an asset or investment opportunity because you expect it to produce a return over time. Depending on what you invest in, this could happen through increases in the value of the asset, income generated by the asset, or both. Examples can include shares, bonds, mutual funds, exchange traded funds, businesses and certain forms of property.
The major difference between saving and investing is therefore not simply where the money is kept. It is what the money is intended to do.
When you save, you are generally prioritizing preservation and accessibility. When you invest, you are generally prioritizing growth and accepting a degree of uncertainty and risk in pursuit of that growth.
This distinction became clearer to me when I started thinking about money in terms of jobs.
Imagine you have ₦500,000. You could put the entire amount into a savings account. The money is still yours, and you can access it when necessary. That money has a job. Its job is to remain available and relatively secure.
Now imagine that another ₦500,000 is placed into a suitable investment. The purpose is different. You are expecting the money to potentially produce a return over time. That money also has a job, but its job is growth.
Neither approach is automatically superior. The appropriate choice depends on what the money is meant to achieve, when you will need it, and how much risk you are prepared and able to accept.
One of the biggest mistakes I noticed in my own thinking was treating every naira as though it needed to perform the same function. But money can have different assignments.
Some money may be for emergencies. Some may be for a bill that needs to be paid next month. Some may be for school fees. Some may be for a business opportunity that could arise later. Some may be intended for a long term financial goal.
Putting all these categories into one account and calling everything savings can make financial planning unnecessarily confusing.
An emergency fund, for example, is primarily designed for unexpected expenses. If your car develops a serious problem, you lose an income source temporarily, your rent suddenly becomes due, or an unexpected family expense appears, you want money that is accessible. You do not necessarily want to depend on an investment that could have fallen in value at exactly the moment you need cash.
That is one reason saving remains important even for people who are serious about investing.
Investing also comes with risk. The value of an investment can rise, but it can also fall. Returns are not guaranteed simply because someone calls something an investment. This is particularly important because people sometimes hear stories about investments that doubled or tripled and forget that every investment has its own risks, costs, conditions and time horizon.
I have learnt that the word investment should never automatically trigger excitement. It should trigger questions.
What exactly am I investing in?
How does it generate returns?
What could cause me to lose money?
How long should I expect to keep the money there?
How easily can I access the money?
What fees or charges are involved?
Who regulates the investment?
What information can I independently verify?
These questions can protect you from confusing legitimate investing with speculation, unrealistic promises or outright scams.
Saving has its own limitation too. Keeping money completely in cash or low return accounts for very long periods can expose you to inflation. Inflation means that the general prices of goods and services increase over time, reducing what a fixed amount of money can purchase.
Think about what ₦100,000 could buy several years ago compared with what the same ₦100,000 can buy today. The number printed on the money may remain ₦100,000, but its purchasing power can change.
This is why simply having money is not always the same thing as becoming wealthier.
That was one of the most important lessons for me. I could look at my account balance and feel good because the number was increasing, but if the cost of everything around me was increasing faster than my money was growing, I was not necessarily becoming wealthier in real terms.
Investing can be one way people attempt to grow their money faster than inflation over a sufficiently long period, although there is no guarantee that a particular investment will achieve that goal.
This is where time becomes extremely important.
Saving is often associated with short term and medium term goals. Investing is more commonly associated with longer term goals because investments can fluctuate in value, and investors may need time to recover from periods of poor performance.
For example, if you know you will need money for an important expense in three months, putting that money into a volatile investment may expose you to unnecessary risk. If the investment falls shortly before you need the money, you may be forced to sell at a loss.
On the other hand, money intended for a long term goal may have a different purpose. If you are investing for a goal that is many years away, you may have more time to tolerate fluctuations, depending on the investment and your personal circumstances.
This is why the question should not simply be, should I save or should I invest?
A better question is, what should each portion of my money be doing?
That question encourages a more balanced approach.
You could have money that is readily accessible for emergencies and immediate obligations. You could have money set aside for short term goals. You could also have money allocated towards carefully researched long term investments.
The proportions will differ from person to person.
Someone with unstable income may place greater importance on building accessible savings before taking significant investment risks. Someone with a stable income, manageable expenses and an established emergency fund may have more room to focus on long term investing. Someone dealing with expensive debt may need to address that debt as part of their overall financial plan before aggressively investing.
This is why personal finance is called personal finance.
There is no universal formula that says every person should save exactly 20 percent or invest exactly 30 percent of their income. Those numbers can be useful examples, but your actual situation matters.
Another difference between saving and investing is the relationship with risk.
Saving generally carries less risk of losing the amount you deposited, especially when using appropriately regulated financial institutions and accounts with applicable protections. Investing, however, exposes you to different types of risk depending on the asset.
A share can lose value. A bond can carry credit and interest rate risks. Property values can change. A business can fail. Even investments that appear attractive can perform differently from expectations.
The fact that an investment has performed well in the past does not guarantee that it will perform well in the future.
This is why I became more interested in understanding investments rather than simply looking for somewhere to put money.
Investing without understanding what you own can be dangerous.
There is also a psychological difference between saving and investing. Saving can feel relatively straightforward because you are watching your money accumulate. Investing requires patience because the value of your investments may move up and down.
Imagine investing ₦1 million and seeing the value temporarily fall to ₦850,000. Someone who never understood investment risk might panic and sell immediately. Someone who understands that markets fluctuate may review the situation, consider the original investment thesis, reassess the risk and make a decision based on information rather than fear.
That does not mean every investment should be held indefinitely. Sometimes changing circumstances justify selling an investment. The important point is that investing requires a different mindset from simply storing money.
Diversification is another concept that becomes important when discussing investing. Rather than putting all your investment money into one asset or one company, diversification involves spreading investments across different assets or categories to reduce the impact of one poor performer. Diversification does not eliminate risk, but it can help manage certain types of risk.
Saving does not require the same type of diversification strategy because its primary purpose is usually accessibility and preservation rather than exposure to a collection of growth assets.
Another thing I learnt is that saving and investing can actually work together.
It is not a competition.
You do not have to become an investor and stop saving. You do not have to save forever and avoid investing completely. A healthy financial strategy can involve both.
For example, imagine someone earns ₦300,000 per month. Instead of asking whether the person should save or invest the entire amount, it may be more useful to consider their expenses, emergency needs, debt obligations, short term goals and long term objectives.
If the person has no emergency savings at all, building an accessible financial cushion may be a priority. Once that foundation is established, they may consider investing money that they can afford to leave invested for longer.
The numbers will differ from one person to another, but the principle remains the same.
Give your money a purpose.
I also realised that increasing income is an important part of this conversation. Saving a small percentage of a very small income can be difficult when basic expenses already consume most of the money. Investing does not magically solve an income problem.
If you earn more, develop valuable skills, build a profitable business, improve your career prospects or create additional legitimate income streams, you may create more room for both saving and investing.
This is where I personally think financial education becomes powerful.
Instead of asking only, where can I put my money?
You start asking, how can I increase my income, control unnecessary expenses, protect my money, save consistently and invest intelligently?
That is a much bigger question.
Saving and investing also differ in their expected relationship with returns. Savings may generate interest depending on the account, but the emphasis is usually on liquidity and safety. Investments are generally made with the expectation of earning a return, but that return comes with uncertainty.
If somebody tells you that an investment will definitely generate extraordinary returns with absolutely no risk, that should immediately encourage deeper investigation.
There is no need to be unnecessarily suspicious of every financial opportunity, but there is also no reason to switch off your critical thinking simply because someone uses impressive financial language.
I have come to appreciate a simple principle: understand the purpose before choosing the tool.
If I need money next week, accessibility matters.
If I need money next year for a known expense, stability and timing matter.
If I am planning for a financial objective many years away, long term growth and investment risk become more relevant.
The closer I get to needing the money, the more important accessibility and preservation can become. The longer the time horizon, the more opportunity there may be to consider investments that fluctuate but potentially offer higher long term returns.
Of course, individual circumstances can change this picture. Tax rules, inflation, interest rates, investment regulations, financial products and economic conditions can all affect the appropriate decision.
For anyone in Nigeria, there is also an additional reason to pay attention to the difference between saving and investing. Inflation and currency movements can significantly affect purchasing power, so looking only at the amount of naira in an account may not provide the complete picture of financial progress.
If ₦1 million becomes ₦1.1 million but the cost of the things you ultimately need has increased substantially, the increase in the account balance does not necessarily represent an equivalent increase in purchasing power.
That does not mean you should rush into investments simply because you are worried about inflation. It means you should understand what your money is doing and what risks you are accepting.
Ultimately, what is the difference between saving and investing? Saving is primarily about putting money aside for future use while prioritising accessibility and preservation. Investing is about committing money to assets or opportunities with the expectation of earning a return over time while accepting investment risk.
Saving can help provide financial stability. Investing can help pursue long term growth. Saving can help you handle the unexpected. Investing can help you work towards future financial goals. Saving and investing are therefore not enemies competing for your attention. They are different financial tools that can serve different purposes.
The mistake is not saving.
The mistake is not investing.
The mistake is expecting one to do the job of the other.
If you keep every naira in savings indefinitely, you may miss opportunities for long term growth and expose your purchasing power to inflation. If you invest every naira you receive and have nothing readily available for emergencies, you may create another problem by making your finances too dependent on assets that can fluctuate in value.
The goal is not simply to have money sitting somewhere.
The goal is to understand why the money is there.
Some money needs to wait safely.
Some money needs to remain available.
Some money needs to work.
Once I started seeing money this way, saving and investing stopped looking like two contradictory financial philosophies. They became two parts of a bigger financial strategy.
And perhaps that is the most important lesson.
Do not simply ask whether you are saving enough.
Do not simply ask whether you are investing enough.
Ask whether you are giving each naira the right job for the stage of life you are currently in.
Because money without a purpose can disappear surprisingly quickly, but money assigned a clear purpose gives you something much more valuable than a growing balance. It gives you a financial direction.

EarnSmartOnline.com.ng is dedicated to helping readers make smarter financial decisions through practical guides on online income, personal finance, technology, digital business, and wealth creation. Our goal is to provide reliable, easy-to-understand, and actionable content that empowers individuals to earn smarter, build sustainable income streams and achieve long-term financial success.
Recommended: Start Earning Online
- Ultimate Affiliate Marketing Program — learn affiliate marketing with a done-for-you sales system ($15). Check it out
- The Newbie Affiliate Guide — the beginner-friendly starter guide (~$6.68). Check it out
- Easy Dollar Maker — earn in dollars uploading AI images and videos from your phone ($17). Check it out
Disclosure: These are affiliate links. If you buy through them, I may earn a commission at no extra cost to you.