
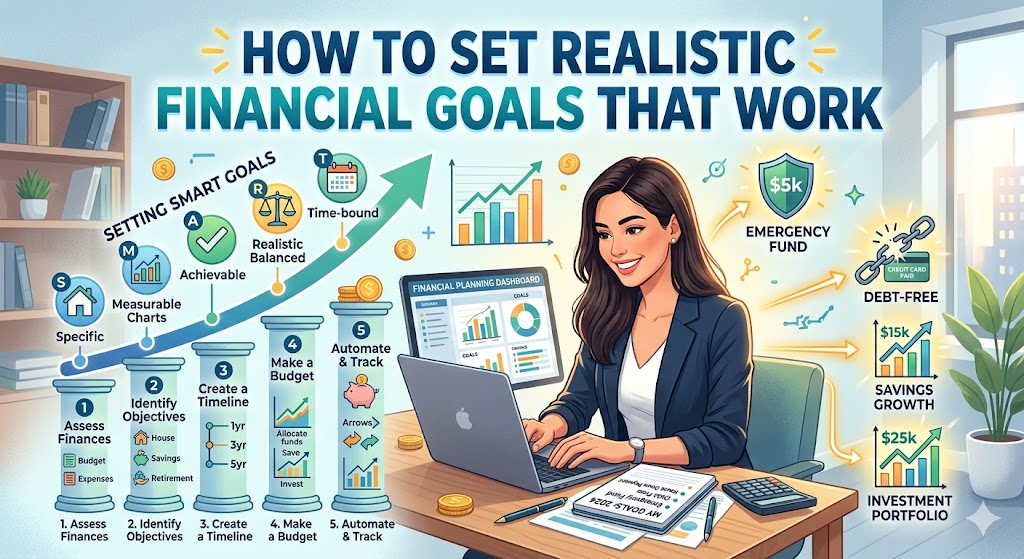
How to Set Realistic Financial Goals That Work
Learning how to set realistic financial goals that work is one of the most important steps you can take towards improving your financial life. Many people want to save more money, eliminate debt, invest, buy a house, start a business, or become financially independent, but wanting these things is not the same as having a workable financial plan. A financial goal becomes powerful when it is specific enough to guide your decisions, realistic enough to pursue consistently, and measurable enough to show you whether you are actually making progress.
The problem is that many financial goals fail before they even begin. Someone may decide that they want to save a huge amount of money within a few months without considering their income, expenses, existing debts, family responsibilities, or unexpected financial demands. When reality eventually clashes with the goal, frustration follows. The person may conclude that saving money is impossible when the real problem was that the target was never properly designed.
Understanding how to set realistic financial goals that work means learning to connect your ambitions with your actual financial situation. It means being honest about where you are, deciding where you want to go, and creating manageable steps between those two points. You do not need to become wealthy before you can start setting financial goals. You simply need a clear understanding of your current situation and a willingness to make consistent decisions.
The first step is to understand your current financial position. Before deciding how much you want to save or invest, take a serious look at your income, expenses, debts, savings, assets, and financial obligations. Your financial goals should be built around reality rather than assumptions. If you earn a particular amount every month, know exactly how much reaches your account and how much is already committed to essential expenses.
Your monthly expenses should also be divided into categories. Consider housing, food, transportation, utilities, education, healthcare, communication, entertainment, debt repayments, family support, subscriptions, and other regular expenses. You may discover that some of your money is disappearing into small expenses that seem insignificant individually but become substantial when added together.
This financial assessment is not supposed to make you feel guilty. Its purpose is to give you information. You cannot successfully manage what you refuse to measure. Once you know where your money is going, you can make better decisions about what needs to change.
After understanding your current position, identify what you actually want to achieve. Financial goals should have meaning behind them. Saving money simply because someone online says you should save more may not be enough motivation to keep you disciplined. A goal becomes more powerful when it is connected to something important in your life.
For example, you might want to build an emergency fund because you do not want an unexpected expense to force you into debt. You might want to clear your debt because you want greater freedom over your income. You might want to save for a house because homeownership is important to you. You might want to invest because you want your money to have the opportunity to grow over time.
When your financial goal has a clear purpose, it becomes easier to make sacrifices for it. You are no longer simply refusing to spend money. You are choosing to direct your money towards something that matters more.
One of the biggest mistakes people make when setting financial goals is trying to accomplish everything at once. They want to save, invest, pay off debt, start a business, buy property, travel, upgrade their lifestyle, and build an emergency fund simultaneously. While ambition is valuable, spreading limited resources across too many objectives can make progress extremely slow.
Prioritisation is therefore essential. Ask yourself which financial goal would make the biggest positive difference to your current situation. If you have expensive debt, reducing that debt may deserve immediate attention. If you have no emergency savings, building a basic financial safety net may be more important than making large investments. If your finances are already stable, you may be able to focus more aggressively on long term investing or another major objective.
Your goals do not have to be achieved in the order that other people achieve theirs. Personal finance is personal. Your financial priorities should reflect your circumstances, responsibilities, income, opportunities, and long term ambitions.
Another important principle when learning how to set realistic financial goals that work is to make your goals specific. Saying “I want to save money” is too vague. How much money do you want to save? What is the money for? When do you want to have it? How much can you realistically save each month?
A stronger goal might be, “I want to save ₦600,000 over the next 12 months by setting aside ₦50,000 each month.” That goal gives you something measurable. You can check your progress every month and immediately know whether you are on track.
Specific goals also make it easier to identify problems. If you planned to save ₦50,000 but consistently save only ₦20,000, you have useful information. Perhaps your income needs to increase. Perhaps your expenses need to decrease. Perhaps the deadline needs to be extended. Instead of simply feeling like a financial failure, you can examine the numbers and adjust the strategy.
Realistic financial goals do not mean thinking small forever. They mean setting targets that challenge you without completely disconnecting from your circumstances. There is an important difference between ambitious and unrealistic.
Suppose you currently have very little savings and your monthly income barely covers your essential expenses. Setting a goal to save several million naira within a few months may create unnecessary pressure. A better approach could be to start with a smaller emergency fund, improve your spending habits, find ways to increase income, and gradually increase your savings target.
The goal should stretch your discipline while remaining achievable with consistent effort. If a goal requires you to behave perfectly every single day with no room for unexpected expenses, it may not be realistic.
Your financial goals should also have deadlines. A goal without a timeframe can remain a wish indefinitely. Deadlines create urgency and make progress easier to measure. However, deadlines should be realistic rather than arbitrary.
If you want to save ₦1,200,000 and can comfortably save ₦50,000 per month, you already have a useful starting point. At that pace, the target would require roughly 24 months, before considering interest or changes in contributions. You could then decide whether increasing your income or reducing certain expenses could shorten the timeline.
Breaking large financial goals into smaller milestones can make them much easier to handle. Instead of constantly thinking about a large final amount, concentrate on the next achievable stage. A large savings target can be divided into monthly or even weekly contributions.
This approach is psychologically powerful because progress becomes visible. Reaching your first milestone gives you evidence that your plan is working. Reaching another milestone builds confidence. Eventually, a goal that once seemed impossible begins to look like the natural result of many small decisions.
Automation can also make financial goals easier to maintain. If your bank or financial platform allows it, consider arranging automatic transfers into a dedicated savings or investment account after receiving your income. The purpose is to reduce the number of decisions you need to make.
When saving depends entirely on whether you remember or feel motivated, consistency can become difficult. There will always be reasons to spend money. Automation helps turn saving into a routine rather than a decision you repeatedly have to negotiate with yourself.
However, automation should not replace awareness. You still need to review your finances regularly. An automatic transfer that worked six months ago may become uncomfortable if your income or expenses change. Your financial system should evolve with your circumstances.
Another important part of setting realistic financial goals is creating an emergency buffer. Life does not always respect your budget. Your phone may break. Your car may need repairs. A family emergency may arise. You may experience an unexpected reduction in income. Without a financial buffer, even a small emergency can disrupt months of progress.
An emergency fund gives your financial plan some breathing room. The appropriate amount depends on your circumstances, income stability, responsibilities, and expenses. The important point is to recognise that unexpected expenses are not necessarily evidence that your financial plan has failed. They are part of real life, which is why your plan should allow room for them.
It is also important to separate needs from wants. This does not mean eliminating every enjoyable expense. A sustainable financial plan should leave room for enjoyment. If your financial strategy requires extreme deprivation indefinitely, you may eventually abandon it.
Instead, look for intentional spending. Ask yourself whether a purchase genuinely contributes to your happiness or whether you are spending because of pressure, comparison, boredom, convenience, or impulse. You may discover that reducing a few unnecessary expenses creates more financial progress without making your life miserable.
Your financial goals should also include income growth where possible. Cutting expenses has limits. There is a minimum amount of money you need to spend to live. Income, however, can potentially increase through skills, employment opportunities, freelancing, business activities, consulting, content creation, or other legitimate sources.
If your current income makes your financial goals difficult to achieve, do not automatically assume that you simply need greater discipline. Sometimes the solution is not to squeeze the same income harder but to find ways to increase the amount coming in.
This is particularly important when your basic expenses already consume most of your income. Saving becomes much easier when the gap between income and expenses increases. Your financial strategy can therefore include both spending management and income development.
Debt should also be considered when setting financial goals. Not all debt has the same characteristics, so it is important to understand the interest rates, repayment terms, and consequences associated with your debts. High cost debt can significantly interfere with your ability to build wealth because part of your future income is already committed to repayments and interest.
Creating a debt repayment target can give you a clear path forward. Rather than saying, “I need to get out of debt,” identify the total amount owed, determine how much you can reasonably allocate towards repayment, and establish milestones. Each reduction in your debt balance represents measurable progress.
At the same time, do not become obsessed with perfection. Financial setbacks happen. You may have a month when you save less than planned. An unexpected expense may force you to use some of your savings. Your income may temporarily decline. None of these events automatically means that your financial goals have failed.
The key is to review what happened and continue. Financial success is rarely built through one perfect year. It is usually built through years of imperfect but consistent decisions.
Regular reviews are therefore essential. Set aside time every month or every few months to examine your progress. Compare your actual savings with your target. Review your expenses. Look at your debt balance. Check whether your income has changed. Consider whether your goals still make sense.
A financial goal that was realistic when you created it may become unrealistic later, and that is not necessarily a bad thing. Your income might increase, your responsibilities might change, or your priorities might shift. Adjusting a goal does not always mean giving up. Sometimes it means becoming more strategic.
It is also important to avoid comparing your financial journey with other people’s visible results. Social media can make it appear as though everyone else is buying houses, driving expensive cars, travelling constantly, investing successfully, and becoming wealthy overnight. What you see rarely represents the complete financial picture.
Someone’s lifestyle may be funded by debt. Someone else may have family support. Another person may have inherited wealth. Someone else may simply be showing their best moments online. Comparing your beginning with somebody else’s middle can create unrealistic expectations.
Your financial goals should be based on your own numbers. Focus on your income, expenses, responsibilities, opportunities, and objectives. Progress is not about looking richer than someone else. It is about becoming financially stronger than you were before.
One useful way to strengthen your financial goals is to connect them to habits. A goal tells you what you want. A habit determines what you repeatedly do to get there. If your goal is to save ₦600,000 in a year, the supporting habit might be transferring ₦50,000 every month. If your goal is to reduce debt, the habit might be making an additional payment whenever you receive extra income. If your goal is to increase income, the habit might be spending several hours each week developing a valuable skill.
This distinction matters because goals can be inspiring at the beginning, while habits keep the process alive after the excitement disappears.
Ultimately, knowing how to set realistic financial goals that work is about creating a financial system that fits your real life. Your goals should be clear, measurable, time bound, prioritised, and connected to your circumstances. They should challenge you without being so unrealistic that you abandon them after a few weeks.
Start where you are. If you have no savings, your first goal does not need to be millions. If you have significant debt, your first objective does not need to be becoming an investor overnight. If your income is limited, your first financial goal might include developing a skill that can increase your earning potential.
Do not underestimate small beginnings. A modest amount saved consistently can become meaningful over time. A small debt payment repeated every month can eventually become freedom. A small improvement in your spending habits can create room for larger financial opportunities later.
The most important thing is to stop treating financial goals as wishes and start treating them as plans. Write down what you want. Put a number beside it. Give it a realistic deadline. Determine what you need to do each month. Track your progress. Review your results. Adjust when necessary. Then repeat the process.
Financial progress is rarely about finding one magical trick that suddenly transforms your life. It is usually about making better decisions consistently for a long enough period for those decisions to produce visible results.
If you want to build a stronger financial future, you do not need to know exactly where you will be ten or twenty years from now. You need to know what your next meaningful step is. Once you take that step, identify the one after it.
That is the real power of learning how to set realistic financial goals that work. You stop waiting for your finances to magically improve and begin deliberately directing your money towards the life you want. Your financial future is shaped by many small choices, and every realistic goal gives those choices a clear direction.
Start with what you can control today. Know your numbers. Choose your priorities. Set realistic targets. Build supportive habits. Track your progress. Increase your income where possible. Protect yourself against emergencies. Learn from setbacks and keep moving.
You may not reach every financial goal exactly when you originally planned, and that is perfectly normal. What matters is that your goals give you direction and your actions keep you moving forward. A realistic financial goal is not merely a number written on paper. It is a commitment to make your money serve a purpose.
When your financial goals are realistic, measurable, meaningful, and supported by consistent habits, they stop being distant dreams and become achievable steps towards greater financial confidence, stability, freedom, and independence.

EarnSmartOnline.com.ng is dedicated to helping readers make smarter financial decisions through practical guides on online income, personal finance, technology, digital business, and wealth creation. Our goal is to provide reliable, easy-to-understand, and actionable content that empowers individuals to earn smarter, build sustainable income streams and achieve long-term financial success.
Recommended: Start Earning Online
- Ultimate Affiliate Marketing Program — learn affiliate marketing with a done-for-you sales system ($15). Check it out
- The Newbie Affiliate Guide — the beginner-friendly starter guide (~$6.68). Check it out
- Easy Dollar Maker — earn in dollars uploading AI images and videos from your phone ($17). Check it out
Disclosure: These are affiliate links. If you buy through them, I may earn a commission at no extra cost to you.



