
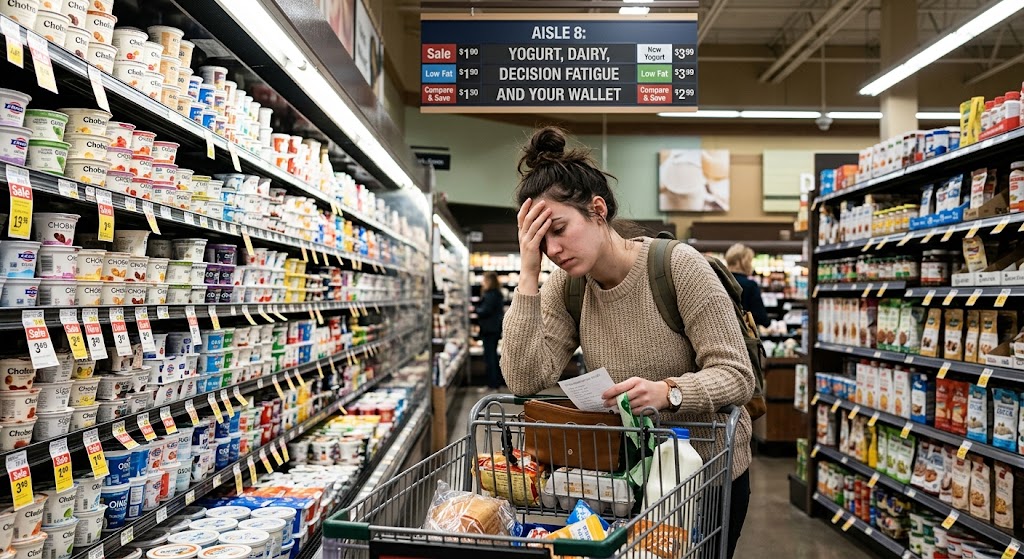
Decision Fatigue and Your Wallet: How Mental Exhaustion Can Quietly Destroy Your Finances
Decision Fatigue and Your Wallet may sound like two completely unrelated subjects until you realise just how many financial decisions you make every single day. From deciding what to eat for breakfast to choosing whether to buy something online, subscribe to a service, take a taxi, save money, borrow money, invest, or simply ignore a tempting offer, your brain is constantly making choices. The more decisions you make, the more mentally tired you can become. And when your mental energy starts running low, your wallet can become one of the first victims.
Decision fatigue is the mental exhaustion that can happen when you are forced to make too many decisions over a period of time. It does not necessarily mean you are physically tired. You can sit comfortably on your bed and still be mentally exhausted from a long day of making choices. The problem becomes particularly interesting when money is involved because financial decisions often require self control, patience and the ability to think about future consequences. When those abilities become weaker, spending can become easier than saving.
The relationship between Decision Fatigue and Your Wallet is therefore worth understanding because financial problems are not always caused by low income. Sometimes they are caused by hundreds of small decisions made when your brain is already tired. You may start the day with good financial intentions, but by evening, your ability to resist unnecessary spending may have weakened considerably.
Imagine waking up with a simple plan. You decide that you will cook at home, avoid unnecessary purchases, save some money and stay away from online shopping. Then your day begins. You have to decide what to wear, what to eat, which route to take, how to respond to messages, which work should come first, whether to attend a meeting, what to buy at the shop and how to solve several problems. By the end of the day, your brain has processed dozens or even hundreds of choices.
Then you receive a notification from an online store offering a product at a seemingly attractive price. You know you do not really need it, but suddenly the decision does not feel as difficult as it would have felt in the morning. You click buy.
That purchase might seem insignificant. But multiply that behaviour by several days, several weeks and several months, and the financial consequences can become surprisingly large.
This is one reason Decision Fatigue and Your Wallet deserve more attention. Your financial behaviour is not determined only by your income, financial knowledge or financial goals. It is also influenced by the mental condition in which you make decisions.
One of the biggest dangers of decision fatigue is that it can make convenience feel more valuable than money. When your brain is exhausted, you may become willing to pay extra simply to avoid another decision. Instead of comparing prices, you buy the first acceptable option. Instead of preparing food, you order something. Instead of checking whether you already have a similar item, you purchase another one. Instead of reviewing your subscriptions, you continue paying for services you barely use.
The interesting part is that none of these decisions necessarily feels financially destructive at the moment. The problem is accumulation.
You may spend a little more on transport because you are tired. You may buy an expensive meal because cooking feels like too much work. You may purchase something online because you do not want to think about whether you actually need it. You may accept an unnecessary fee because challenging it requires effort. You may renew a subscription because cancelling it requires several steps.
Your wallet does not care whether the individual expense felt small. It only records the money leaving.
Decision Fatigue and Your Wallet are connected particularly strongly in the modern digital economy because businesses have become extremely good at reducing the amount of thinking required before spending. Shopping platforms remember your card details. Online stores recommend products based on previous behaviour. Food delivery apps show meals that can be ordered within seconds. Streaming platforms encourage automatic subscriptions. Advertising follows you across different platforms. Promotions create urgency. One click can turn a passing desire into a completed purchase.
The easier spending becomes, the less mental effort you need to make the decision.
That can be convenient, but convenience has a financial price when it removes the pause between wanting something and buying it.
This is why one of the simplest ways to protect your wallet is to create friction around unnecessary spending. You could remove saved card details from shopping platforms. You could disable certain promotional notifications. You could wait before purchasing nonessential items. You could establish a rule that anything above a particular amount requires 24 hours of consideration.
The goal is not to make spending impossible. The goal is to prevent exhausted emotions from making financial decisions on your behalf.
Another important part of Decision Fatigue and Your Wallet is the role of defaults. People tend to continue with an existing choice because making a new decision requires effort. This can be financially dangerous when the default is expensive.
For example, imagine subscribing to several digital services. Each monthly payment might appear manageable. But because the payments happen automatically, you do not have to make a fresh decision every month. The money simply leaves your account.
This is convenient for the service provider because convenience encourages retention. But it can be expensive for you if you forget about the subscriptions.
The same principle applies to insurance, banking fees, mobile plans, software subscriptions, memberships and other recurring expenses. Your wallet can slowly lose money simply because you are too mentally busy to revisit old decisions.
A powerful financial strategy is therefore to make good decisions once and automate them where appropriate. Instead of asking yourself every month whether you should save, automate a reasonable amount into savings immediately after receiving income. Instead of repeatedly deciding how much to spend on certain categories, establish a budget. Instead of constantly wondering whether you should invest, create a long term investment strategy that matches your circumstances and risk tolerance.
Automation can protect your future self from your tired self.
But automation should not mean ignoring your finances completely. You still need periodic reviews to make sure the systems you created remain suitable.
Decision fatigue can also influence food spending. This is one of the easiest areas to observe. After a stressful day, the thought of preparing food, shopping for ingredients, cooking and cleaning can feel overwhelming. Ordering food becomes attractive because it removes multiple decisions at once.
The financial issue is not that ordering food is always bad. There is nothing wrong with paying for convenience when it fits your budget. The problem occurs when convenience becomes the default response to mental exhaustion.
A person may believe they have a food budget, but if they repeatedly make expensive food decisions when exhausted, the budget can disappear without any single dramatic purchase.
The same thing happens with transportation. Someone may normally use public transport or a cheaper option but choose a more expensive alternative after a tiring day because they want to reduce stress. Again, one decision may not matter much. Repeated behaviour can.
This is why controlling Decision Fatigue and Your Wallet is not about becoming extremely strict with every naira you spend. It is about identifying the moments when you are most vulnerable to making decisions that conflict with your financial goals.
For some people, that moment is late at night. For others, it is immediately after receiving income. For others, it is after a stressful workday. Some people spend more when they are bored. Others spend when they are celebrating. Some spend when they are emotionally upset.
Your spending triggers may not be obvious until you start observing them.
One useful exercise is to look at your recent transactions and ask yourself what was happening emotionally when you made the purchases. Were you hungry? Tired? Angry? Bored? Excited? Stressed? In a hurry? Trying to reward yourself?
You might discover that your financial problem is not simply a lack of discipline. You may have designed your financial life in a way that repeatedly forces you to make difficult decisions when your mental energy is at its lowest.
That is an important distinction.
If you constantly rely on willpower, you are fighting the same battle repeatedly. A better strategy is to redesign your environment.
For example, if you know you frequently buy unnecessary items after seeing social media advertisements, reduce your exposure to promotional content. If you tend to overspend when shopping online at night, avoid browsing shopping platforms when you are tired. If you spend too much money eating outside because you do not know what to cook, create a simple list of meals you can prepare without much thinking.
Financial discipline becomes easier when the right decision is also the convenient decision.
This is one of the most practical lessons from Decision Fatigue and Your Wallet. You do not necessarily need more motivation. You may need fewer unnecessary decisions.
Consider your monthly budget. If every single purchase requires you to calculate whether you can afford it, your financial life can become mentally exhausting. A simpler system may work better. You can divide your income into clear categories for essential expenses, savings, investments, personal spending and other priorities. The exact percentages will depend on your circumstances, but the principle is simple. Give your money a job before your emotions give it one.
A clear financial system reduces the number of decisions you need to make later.
Another powerful approach is to separate wants from decisions that genuinely matter. Not every purchase deserves a lengthy debate. Spending ten minutes analysing whether to buy a small inexpensive item can itself become exhausting. The purpose of a financial system is to make ordinary decisions easier so that you can reserve serious thinking for major financial choices.
This is particularly important when making decisions involving debt. Borrowing money when mentally exhausted can be dangerous because debt decisions often have consequences that last much longer than the emotional state that produced them.
A person may take a loan because they urgently want relief from a financial problem. But the relief can be temporary while the repayment obligation continues. Before taking on debt, it is worth stepping away from the immediate pressure and asking what the total repayment will be, whether the borrowing is genuinely necessary, whether there is another solution and how the repayment will affect future cash flow.
Never allow a temporary emotional state to make a permanent financial commitment without careful consideration.
Decision fatigue can also affect investing. When people become overwhelmed by financial information, they may either make impulsive decisions or avoid investing altogether. They may jump between strategies, react emotionally to market movements or constantly change their plans.
A simple, diversified and long term strategy that suits your circumstances can reduce unnecessary decision making. However, investment decisions should always be based on your own financial situation, objectives and risk tolerance rather than on excitement, social media trends or pressure from other people.
There is another side to Decision Fatigue and Your Wallet that deserves attention: decision fatigue can make people vulnerable to marketing.
Advertisers understand that people do not have unlimited attention. Modern advertising often attempts to reduce thinking time by creating urgency, scarcity and emotional pressure. “Only today.” “Last chance.” “Limited stock.” “People are buying this right now.”
When you are mentally exhausted, these messages can become more persuasive because you may not want to spend time evaluating whether the offer is genuinely valuable.
A useful rule is to separate urgency from importance. Something can be urgent in an advertisement without being important in your life.
You do not need to respond to every financial opportunity immediately.
Sometimes the smartest financial decision is to do nothing.
That sounds simple, but doing nothing can be extremely powerful. Every purchase you avoid is money that remains available for something more important. Every subscription you cancel creates recurring savings. Every unnecessary fee you prevent increases the amount of money working towards your goals.
The relationship between Decision Fatigue and Your Wallet also becomes clearer when you understand the concept of opportunity cost. Money spent on something unnecessary cannot be used somewhere else. That does not mean you should feel guilty about every enjoyable purchase. Money is meant to serve your life, not control it. But intentional spending is very different from unconscious spending.
If you spend money because something genuinely brings you value, that is a decision. If you spend money simply because you are mentally exhausted and want the decision to disappear, that is something worth examining.
One of the best ways to reduce financial decision fatigue is to establish personal rules before you become tired.
Decide in advance how much you will save. Decide which bills will be automated. Decide how frequently you will review subscriptions. Decide how long you will wait before making large purchases. Decide which categories deserve more spending and which categories need limits.
Precommitment is powerful because your future decisions are often easier when your present self has already established the rules.
You can also create a “low energy” financial plan. This could include simple meals at home, a predetermined transport budget, a temporary spending freeze on nonessential purchases and a short list of activities that do not cost much money.
The idea is not to punish yourself for being tired. It is to protect yourself from making expensive decisions simply because you are tired.
Another important lesson is that financial simplicity can be more valuable than financial perfection. You do not need a complicated spreadsheet with dozens of categories if you cannot maintain it. You need a system that you can actually follow.
The best budget is not necessarily the most detailed budget. It is the budget that survives real life.
If tracking every small expense makes you abandon budgeting after two weeks, simplify the system. If managing several bank accounts creates confusion, organise them in a way that makes sense for you. If you constantly forget bills, automate reminders or payments where appropriate.
The goal is to reduce mental clutter.
Your wallet often reflects your environment more than your intentions. You may genuinely want to save money while surrounding yourself with constant opportunities to spend it. You may want to eat cheaply while keeping food delivery apps one click away. You may want to stop impulse shopping while receiving promotional notifications throughout the day.
Your intentions matter, but your environment matters too.
This is why understanding Decision Fatigue and Your Wallet can change the way you approach personal finance. Instead of asking only, “Why am I not disciplined enough?” you can ask, “What decisions are draining my mental energy, and how can I make my financial life simpler?”
That question leads to better solutions.
Perhaps you need fewer subscriptions. Perhaps you need automatic savings. Perhaps you need a weekly meal plan. Perhaps you need a waiting period for large purchases. Perhaps you need to stop shopping when you are emotionally exhausted. Perhaps you need a simple spending allowance that allows you to enjoy your money without constantly feeling guilty.
Financial freedom is not simply about earning more money. Earning more certainly helps, but keeping and directing money effectively matters too. If your spending habits automatically expand every time your income increases, higher earnings may not produce the financial progress you expect.
Your mind and your money are connected.
When you are rested, focused and intentional, financial decisions can look very different from the choices you make when you are overwhelmed. Recognising that does not excuse irresponsible spending. Instead, it gives you a more practical way to prevent it.
The next time you find yourself about to make an unnecessary purchase after a long and stressful day, pause for a moment. Ask yourself whether you genuinely want the item or whether you simply want the decision to be over. Ask whether you would still buy it tomorrow morning. Ask what else that money could do for you.
That small pause can be surprisingly powerful.
Decision Fatigue and Your Wallet is ultimately a reminder that financial success is not built only through big decisions. It is also built through the thousands of small choices that happen when nobody is watching. The meal you decide to cook instead of ordering. The subscription you cancel. The purchase you postpone. The fee you question. The money you automatically save. The temptation you ignore.
None of these decisions may make you rich overnight.
But together, they can completely change the direction of your finances.
The goal is not to eliminate every enjoyable expense or turn your life into an endless exercise in restriction. The goal is to make your money decisions intentional. Spend where spending genuinely improves your life. Save where saving supports your future. Automate what can be automated. Simplify what can be simplified. And most importantly, recognise that your financial judgement can change when your mental energy runs low.
Your wallet does not only need more money. Sometimes it needs fewer decisions.
And perhaps that is the biggest lesson of all. Financial discipline is not always about having extraordinary willpower. Sometimes it is about building an ordinary system that protects you when your willpower disappears.
When you reduce unnecessary decisions, you create more mental space for the decisions that actually matter. And when you protect that mental space, you also protect something else: your money.
So before blaming yourself for every unnecessary purchase, take a closer look at the circumstances surrounding your spending. You might discover that the problem is not simply that you love spending. You might simply be making too many decisions, becoming mentally exhausted and reaching for the easiest option.
Recognising that pattern is the first step.
Changing your environment is the next.
And over time, those small changes can make a very big difference to both your financial health and your peace of mind.

EarnSmartOnline.com.ng is dedicated to helping readers make smarter financial decisions through practical guides on online income, personal finance, technology, digital business, and wealth creation. Our goal is to provide reliable, easy-to-understand, and actionable content that empowers individuals to earn smarter, build sustainable income streams and achieve long-term financial success.
Recommended: Start Earning Online
- Ultimate Affiliate Marketing Program — learn affiliate marketing with a done-for-you sales system ($15). Check it out
- The Newbie Affiliate Guide — the beginner-friendly starter guide (~$6.68). Check it out
- Easy Dollar Maker — earn in dollars uploading AI images and videos from your phone ($17). Check it out
Disclosure: These are affiliate links. If you buy through them, I may earn a commission at no extra cost to you.



