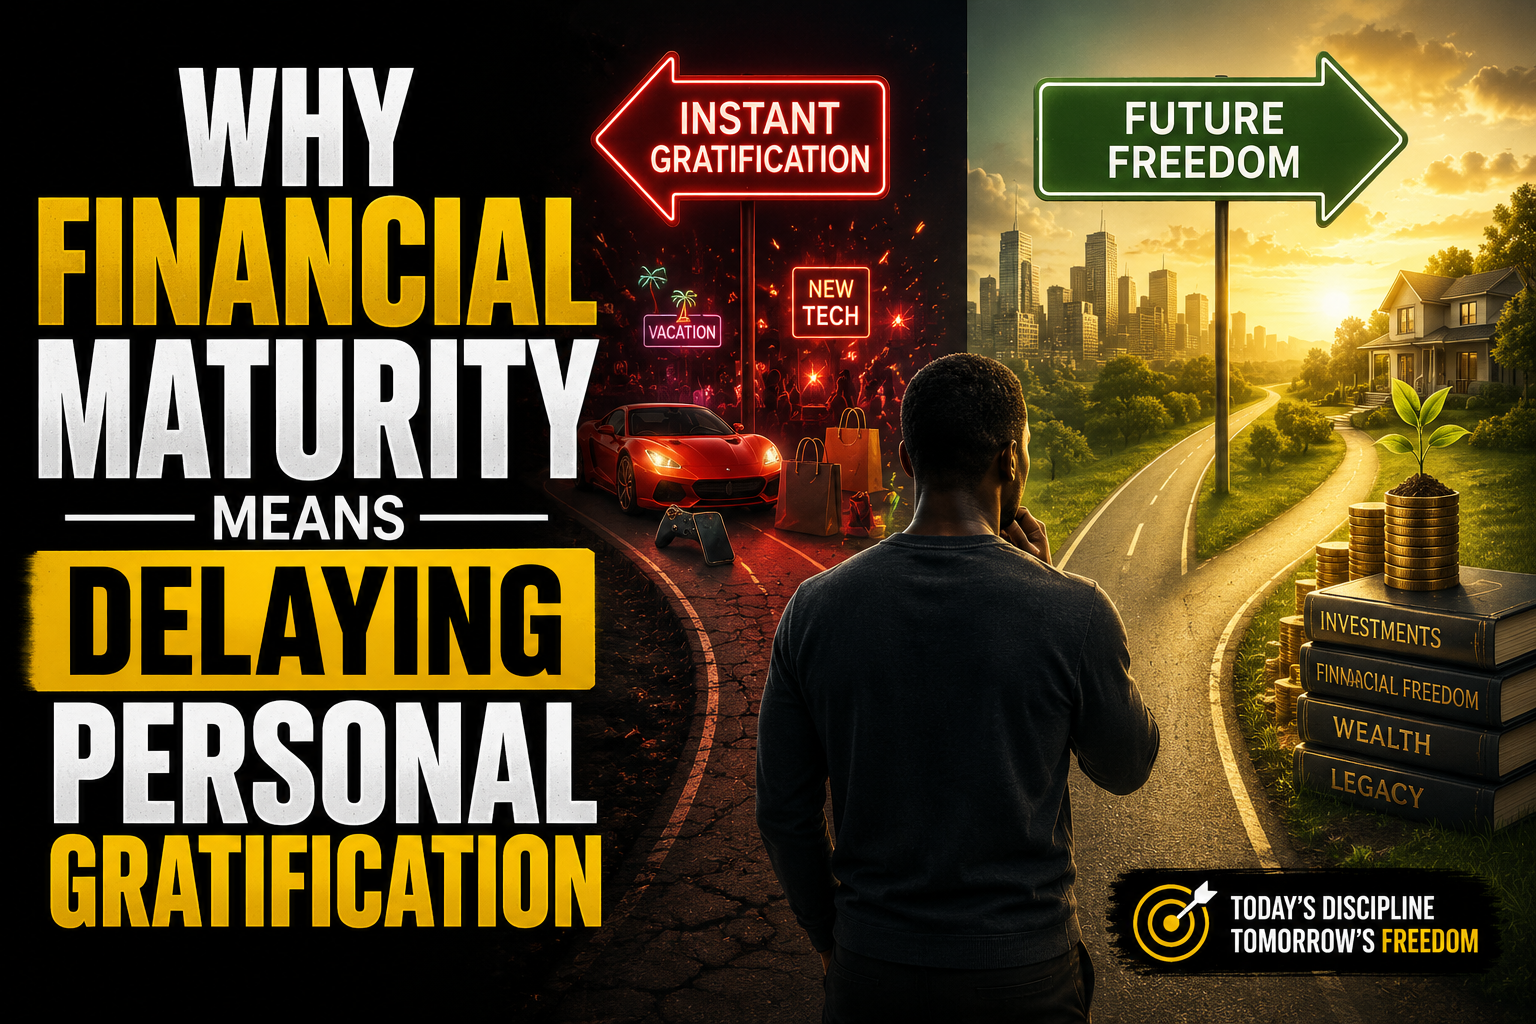
Why Financial Maturity Means Delaying Personal Gratification
Every person dreams of living a comfortable life, enjoying financial freedom, owning valuable assets, and having enough money to make choices without constantly worrying about bills. Yet, despite earning salaries, running businesses, or receiving regular income, millions of people remain trapped in financial stress year after year. The difference is rarely determined by intelligence, educational qualifications, family background, or even income level. More often than not, it comes down to one simple but powerful principle: the ability to delay personal gratification.
Financial maturity means making decisions today that protect and improve your future, even when those decisions require sacrifice. It is the discipline to choose long-term security over short-term pleasure, permanent wealth over temporary excitement, and lasting freedom over instant satisfaction. While delaying personal gratification may seem difficult in a world built around convenience and instant rewards, it remains one of the strongest foundations of financial success.
Modern society encourages people to satisfy every desire immediately. Online shopping allows purchases with a single click. Food can be delivered within minutes. Entertainment is available instantly through streaming platforms. Social media constantly exposes people to luxurious lifestyles, expensive vacations, designer clothing, and the newest gadgets. Credit facilities make it possible to own things before earning enough money to pay for them. All these conveniences quietly encourage a dangerous financial habit: spending before thinking.
The human brain naturally prefers immediate rewards over future benefits. This psychological tendency explains why many people struggle to save money even when they know saving is important. It explains why expensive phones sell out despite many buyers already owning functional devices. It explains why people celebrate payday with unnecessary spending only to struggle before the next salary arrives. Financial maturity begins when a person learns to control these natural impulses instead of allowing them to control every financial decision.
Delaying personal gratification does not mean living a miserable life or refusing to enjoy the fruits of hard work. It simply means understanding that timing matters. It means recognising that every financial decision carries consequences beyond the present moment. Buying something today may prevent investing in an opportunity tomorrow. Taking on unnecessary debt today may delay financial independence for years. Choosing temporary pleasure repeatedly often creates permanent financial pressure.
One of the biggest misconceptions about wealth is that wealthy people buy everything they want. In reality, financially mature individuals often postpone purchases, negotiate better deals, compare alternatives, and avoid spending simply because they can afford to. Their discipline is usually invisible. Society notices the luxury car after years of careful financial planning, but it rarely sees the countless temptations they ignored to reach that point.
Financial maturity also changes how people define success. Immature financial thinking measures success by possessions. Mature financial thinking measures success by stability, freedom, flexibility, and peace of mind. Someone with a modest lifestyle, no debt, growing investments, and substantial savings may be financially stronger than someone driving expensive cars while struggling with overwhelming monthly repayments.
One of the greatest enemies of financial maturity is emotional spending. Many purchases have little to do with actual need. People shop because they feel stressed, bored, lonely, disappointed, or anxious. Retail therapy provides temporary emotional relief but often leaves behind lasting financial regret. Delaying gratification requires recognising emotional triggers and refusing to allow feelings to dictate financial behaviour.
Social pressure makes delaying gratification even harder. People constantly compare themselves with friends, neighbours, colleagues, celebrities, and social media influencers. They feel pressured to own the latest smartphone, wear expensive fashion brands, organise elaborate celebrations, or upgrade perfectly functional possessions simply because others have done so. Financial maturity requires confidence to ignore these pressures and make decisions based on personal financial goals rather than public expectations.
Advertising also plays a significant role in encouraging instant gratification. Companies spend billions understanding consumer psychology. They know how colours, words, images, discounts, countdown timers, and limited-time offers influence buying decisions. They create urgency where none actually exists. Financial maturity means recognising these marketing techniques and refusing to let artificial urgency dictate real financial decisions.
Delayed gratification strengthens every other financial habit. Saving becomes easier because unnecessary spending decreases. Investing becomes possible because money remains available after essential expenses. Emergency funds grow naturally because impulse purchases no longer consume disposable income. Debt reduces because borrowing becomes less attractive when wants are separated from genuine needs.
One of the simplest ways to measure financial maturity is to observe how someone reacts when receiving unexpected income. An immature response often involves immediate spending on luxury items, entertainment, or unnecessary upgrades. A mature response considers long-term priorities first. Outstanding debts may be reduced. Emergency savings may be strengthened. Investments may be increased. Future financial security receives attention before present enjoyment.
Financial maturity also affects career decisions. Some people reject opportunities to learn valuable skills because the training requires time, money, or temporary sacrifice. Others invest in education, certifications, and personal development even when immediate rewards are not visible. Years later, these investments frequently produce significantly higher income, greater career stability, and expanded opportunities. Delaying gratification allows people to invest in themselves instead of constantly consuming.
Business owners experience the same principle. Many successful entrepreneurs delay personal luxury while reinvesting profits into business expansion. Instead of purchasing expensive vehicles after their first profitable year, they improve operations, hire better staff, expand marketing, upgrade equipment, or launch new products. Their willingness to sacrifice immediate comfort often creates businesses capable of generating wealth for decades.
Parents demonstrate financial maturity whenever they prioritise their children’s future over their own temporary pleasures. Paying school fees, investing in education, maintaining health insurance, building savings, and creating financial stability require sacrifices that may not provide immediate excitement. Yet these decisions often transform future generations.
The power of delayed gratification becomes even more remarkable because of compound growth. Small financial sacrifices made consistently over many years can produce extraordinary results. Saving a modest amount each month may appear insignificant initially. However, when combined with consistent investing and compound returns, these disciplined habits can eventually generate financial independence. Wealth is often built quietly through patience rather than dramatically through sudden windfalls.
Many lottery winners provide powerful lessons about financial immaturity. Despite receiving enormous wealth almost overnight, many eventually return to financial hardship because spending habits remain unchanged. Income alone never guarantees wealth. Without maturity, larger income often produces larger expenses instead of greater financial security.
Debt frequently reflects the absence of delayed gratification. While certain debts, such as carefully managed business or educational investments, may create future value, much consumer debt exists because individuals wanted immediate enjoyment without waiting until they could genuinely afford it. Credit cards, buy-now-pay-later schemes, and personal loans often transform today’s pleasure into tomorrow’s burden.
Financial maturity also improves relationships. Money disagreements remain one of the leading causes of conflict among couples and families. Partners who share disciplined financial values generally experience fewer conflicts regarding spending, saving, borrowing, and investing. Mutual willingness to delay gratification allows families to pursue common goals such as home ownership, children’s education, retirement planning, or business investment.
Children naturally imitate financial behaviour they observe. Parents who constantly spend impulsively unintentionally teach similar habits. Conversely, parents who explain budgeting, saving, investing, and disciplined spending provide lifelong financial education. Delayed gratification therefore becomes not only a personal habit but also a legacy passed to future generations.
Technology has made financial discipline simultaneously easier and more difficult. Budgeting applications, investment platforms, and digital banking tools simplify money management. However, the same technology also makes spending almost effortless. One-click purchases remove the psychological barriers that cash transactions once created. Financial maturity requires intentionally using technology to strengthen discipline rather than weaken it.
One effective strategy for developing delayed gratification involves introducing waiting periods before making purchases. Instead of buying immediately, financially mature individuals often wait twenty four hours, several days, or even several weeks before completing non-essential purchases. During this period, emotional excitement usually decreases, allowing logical thinking to replace impulsive decision making.
Setting clear financial goals also strengthens delayed gratification. People willingly sacrifice present pleasures when they clearly understand future rewards. Saving becomes easier when linked to specific objectives such as buying a home, building investment portfolios, funding children’s education, achieving retirement security, or starting a business. Vague intentions rarely overcome immediate temptation, but meaningful goals create powerful motivation.
Financial maturity requires distinguishing between price and value. Expensive items are not always valuable, and inexpensive items are not always economical. Mature consumers evaluate purchases based on long-term usefulness rather than emotional excitement or social prestige. They ask whether a purchase will improve their lives meaningfully or simply provide temporary satisfaction.
Minimalism has become increasingly popular partly because it encourages delayed gratification. Rather than accumulating endless possessions, financially mature individuals often focus on owning fewer but higher-quality items. They understand that constant consumption rarely produces lasting happiness. Instead, reducing unnecessary possessions often increases financial freedom while decreasing stress.
Another characteristic of financial maturity is learning to appreciate progress rather than perfection. Many people become discouraged because financial independence seems distant. As a result, they abandon saving altogether. Mature individuals celebrate consistent improvement. They recognise that every debt reduced, every investment made, every unnecessary purchase avoided, and every savings contribution strengthens their financial future.
Financial maturity also involves accepting that some opportunities should be rejected regardless of potential excitement. Attractive investment schemes promising unrealistic returns frequently exploit impatience. Mature investors understand that sustainable wealth usually grows gradually. They resist shortcuts because they recognise that extraordinary promises often conceal extraordinary risks.
The workplace provides daily opportunities to practise delayed gratification. Spending entire salary increases immediately creates lifestyle inflation. Instead, financially mature professionals often maintain previous living standards while directing additional income toward investments, debt reduction, or savings. This simple habit accelerates wealth creation dramatically over time.
Retirement planning perhaps illustrates delayed gratification better than any other financial decision. Contributions made today may not be used for decades. Nevertheless, those willing to sacrifice a small percentage of present income often enjoy greater comfort, dignity, and independence later in life. Those who postpone retirement planning frequently discover that time cannot easily be recovered.
Delayed gratification also protects mental health. Financial stress creates anxiety, sleeplessness, relationship conflict, and reduced productivity. Building financial reserves through disciplined decisions creates confidence during uncertain periods. Emergencies become manageable rather than catastrophic. Unexpected expenses become inconveniences instead of disasters.
One important lesson many successful people share is that wealth creation rarely depends on extraordinary intelligence. Instead, it depends on ordinary decisions repeated consistently over long periods. Refusing unnecessary purchases, maintaining budgets, investing regularly, avoiding destructive debt, and living below one’s means may appear unremarkable individually. Together, however, these habits produce extraordinary financial outcomes.
Financial maturity encourages gratitude. Instead of constantly chasing newer possessions, mature individuals appreciate what they already own while working patiently toward future goals. Gratitude reduces unnecessary consumption because satisfaction no longer depends entirely on acquiring more material possessions.
It is also important to understand that delayed gratification extends beyond money itself. It influences health, education, relationships, business, career advancement, and personal development. The discipline required to save money resembles the discipline required to exercise regularly, study consistently, build successful businesses, or maintain meaningful relationships. Mastering delayed gratification in one area often strengthens discipline across every area of life.
The financial world continually rewards patience. Investments appreciate gradually. Businesses expand steadily. Careers develop through years of experience. Professional reputations strengthen through consistent reliability. Financial maturity recognises these natural timelines instead of demanding immediate rewards.
Many people mistakenly believe they will become financially disciplined after earning more money. Unfortunately, financial habits usually scale with income. Those unable to delay gratification while earning little often continue struggling after earning significantly more because spending simply rises alongside income. Financial maturity must therefore develop before wealth arrives, not afterwards.
There is profound freedom in knowing that your decisions are guided by wisdom instead of impulse. Every unnecessary purchase resisted strengthens self-control. Every investment made strengthens future security. Every debt avoided protects tomorrow’s opportunities. Every disciplined financial decision becomes another brick in the foundation of lasting wealth.
Ultimately, financial maturity means recognising that true wealth is not measured by how quickly you can satisfy every desire but by how wisely you choose which desires deserve your resources. Delaying personal gratification is not about denying yourself happiness. It is about choosing greater happiness over temporary excitement, lasting security over momentary pleasure, and permanent freedom over short-lived satisfaction.
The people who achieve genuine financial independence are rarely those who chase every pleasure the moment it appears. They are usually the individuals who understand that today’s sacrifice can become tomorrow’s opportunity, today’s discipline can become tomorrow’s abundance, and today’s patience can become tomorrow’s prosperity. Financial maturity is therefore not simply about managing money. It is about managing yourself. Once self-control becomes stronger than impulse, money becomes easier to keep, easier to grow, and far more capable of creating the secure, meaningful, and fulfilling life that so many people desire.

EarnSmartOnline.com.ng is dedicated to helping readers make smarter financial decisions through practical guides on online income, personal finance, technology, digital business, and wealth creation. Our goal is to provide reliable, easy-to-understand, and actionable content that empowers individuals to earn smarter, build sustainable income streams and achieve long-term financial success.
Recommended: Start Earning Online
- Ultimate Affiliate Marketing Program — learn affiliate marketing with a done-for-you sales system ($15). Check it out
- The Newbie Affiliate Guide — the beginner-friendly starter guide (~$6.68). Check it out
- Easy Dollar Maker — earn in dollars uploading AI images and videos from your phone ($17). Check it out
Disclosure: These are affiliate links. If you buy through them, I may earn a commission at no extra cost to you.